Merchant offers are card-linked discounts that provide statement credits or other bonuses at participating retailers, restaurants, hotels and other businesses. This is on top of the rewards your card normally earns.
Before filling your gas tank, booking a flight or placing an online order, take a moment to check your Citi account. You may have a targeted offer worth $5, $20 or more on a purchase you already planned to make.
Once you know where to look, these offers can put meaningful money back in your pocket on expenses you’d have to cover anyway.
What are Citi Merchant Offers?
Citi calls its card-linked discount program Citi Merchant Offers. To use a deal, activate the offer in your account, then make a qualifying purchase with the enrolled card. There are no coupon codes to enter at checkout.
Offers either provide a fixed statement credit after you meet a spending requirement or a percentage back on an eligible purchase. For example, you might find an offer for $20 back after spending $100 or more at a hotel or 5% back at the gas pump, subject to a maximum credit.
Like Amex Offers and Chase Offers, offers are targeted, so the retailers, discounts and terms you see may differ from those available to another cardholder or even on another Citi card in your own account.
Related: Why the Citi Strata Premier and Strata cards are a great pair
Which cards have access to Citi Merchant Offers?
Most personal Citi credit cards have access to Merchant Offers, though there isn’t an official list of which cards do or do not qualify.
The quickest way to verify which of your cards are eligible is to visit Citi’s Merchant Offers page and log in. If you have multiple eligible cards, use the drop-down menu to switch between them.
All of my Citi cards — both current and past — have (or had) access to Citi Offers. Right now, each of my Citi cards has over 300 offers available.
Related: The best time to apply for these popular Citi credit cards, based on offer history
How to find and use Citi Merchant Offers
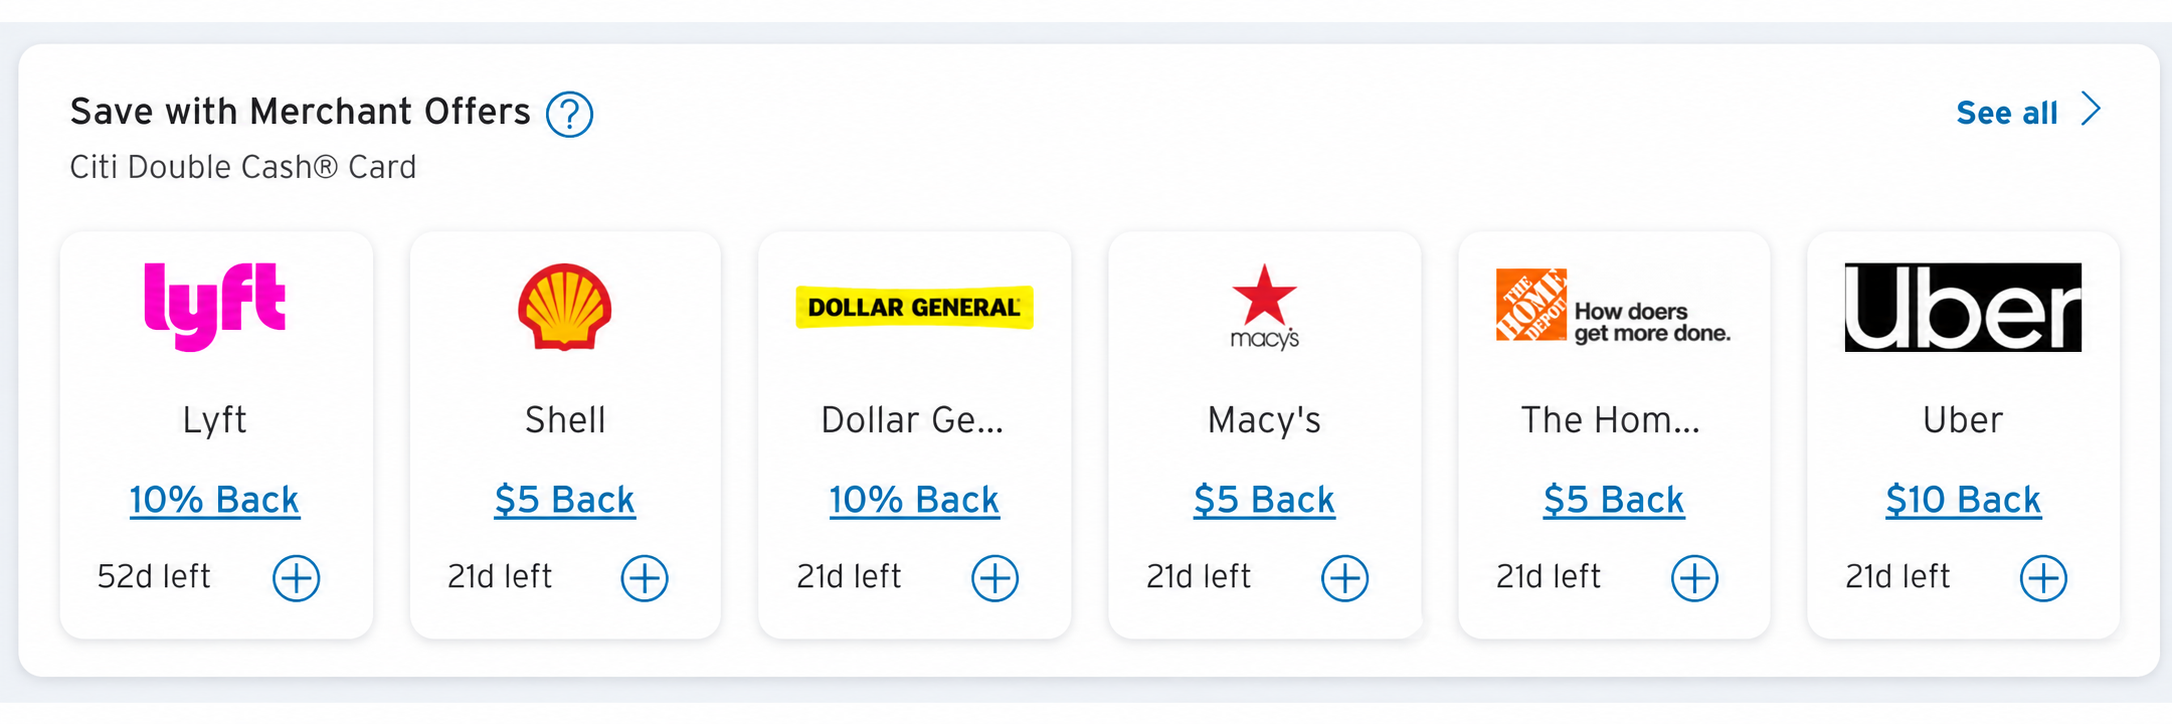
I personally check my Citi offers when I’m already paying my bill or checking my recent transactions. My account shows a portion of my available offers at the bottom and I can click through to see all.
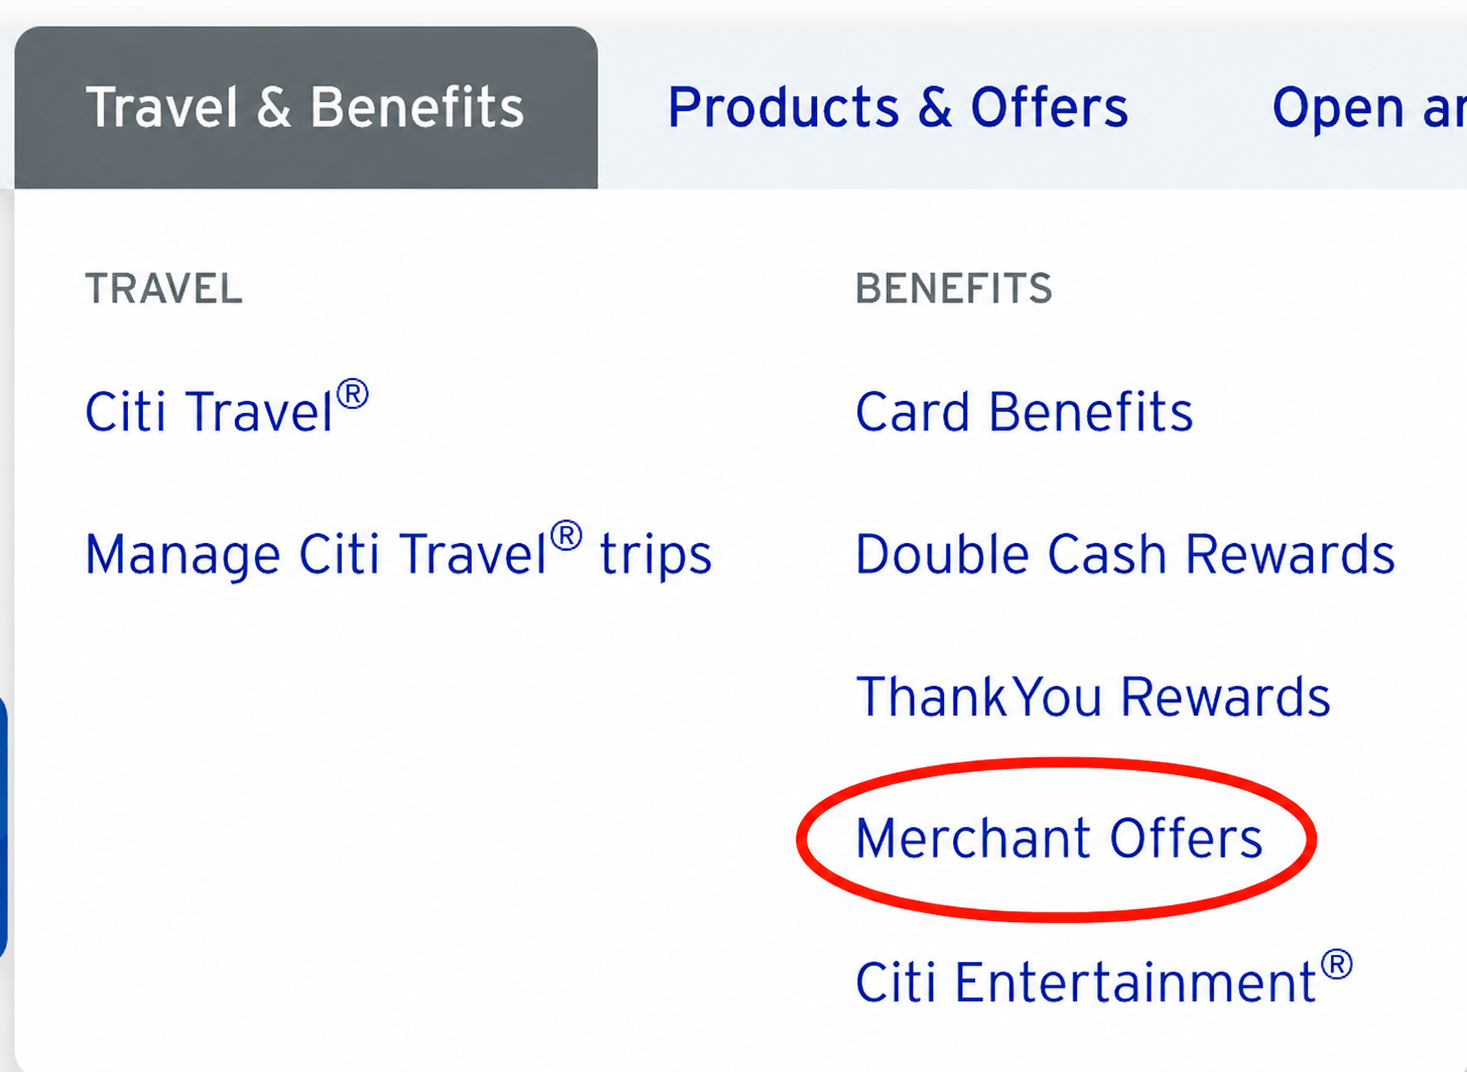
You can also navigate to your offers by logging in online, hovering over “Travel & Benefits” in the top navigation menu and selecting “Merchant Offers.” You’ll similarly find offers in your Citi mobile app or by bookmarking the Citi Merchant Offers page and heading right there.
Once you see an offer you like, click the plus sign to add it to the card shown. Confirm that Citi marked the offer as enrolled before making your purchase.
How long do Citi Merchant Offers take to post?
In my experience, most offers post within two to three weeks, though timing can vary by offer.
If you don’t see the credit post automatically, you can follow up after that timeline. I personally don’t follow up on small statement credits, but for larger rebates, I save screenshots of the enrollment confirmation, offer terms and proof of purchase in case I need documentation.
Related: Who should get the Citi Strata Card?
What types of deals can you find through Citi Merchant Offers?
Citi divides offers into five categories:
- Dining
- Entertainment
- Health and wellness
- Shopping
- Travel
The exact merchants change frequently. Some offers provide a flat amount back after you meet a minimum spending requirement, while others award a percentage back up to a stated limit.
It can be tempting to scroll through the many offers, but now that I have an idea of the types of offers it often includes, I tend to navigate straight to the travel section.
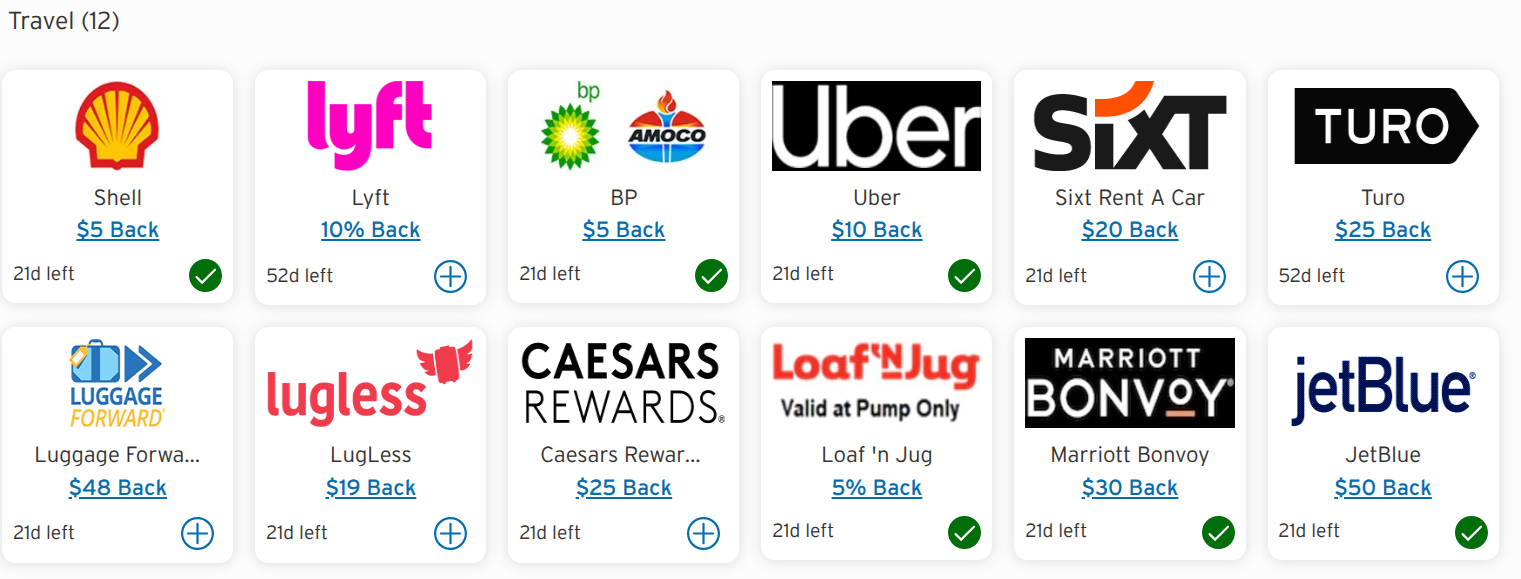
Occasionally, I’ll also look for specific retailers if I know I’ve seen them before. For example, rideshares like Lyft are often featured.
Related: How to maximize online shopping portals for your purchases
What to know about Citi Merchant Offers
With Citi Merchant Offers, the headline discount rarely tells the whole story. Click through to check spending requirements, expiration dates, rebate caps and other restrictions.
Here’s what you should look for.
You may not be able to stack promotions
Some offers explicitly state that they can’t be combined with other promotions.
I see this in my restaurant offers, where featured restaurants often overlap with other dining rewards programs (such as SkyMiles Dining). I usually need to choose between earning miles with my preferred travel dining program or if Citi Offers makes more sense.
Citi Merchant Offers don’t always stack with SimplyMiles, American Airlines’ card-linked program. Enrolling in one will often negate the other, so choose the reward you prefer rather than counting on both to post.
An offer may only be available to certain customers
The merchant name and spending requirement aren’t the only eligibility rules that matter. Some offers are limited to new customers or people signing up for a subscription account rather than a one-time purchase.
A cardholder who focuses only on the credit could easily miss these major restrictions.
Some offers can be redeemed more than once
Don’t assume an offer disappears after one qualifying purchase.
For example, I have an offer for $5 back on a Shell fuel purchase of at least $40.
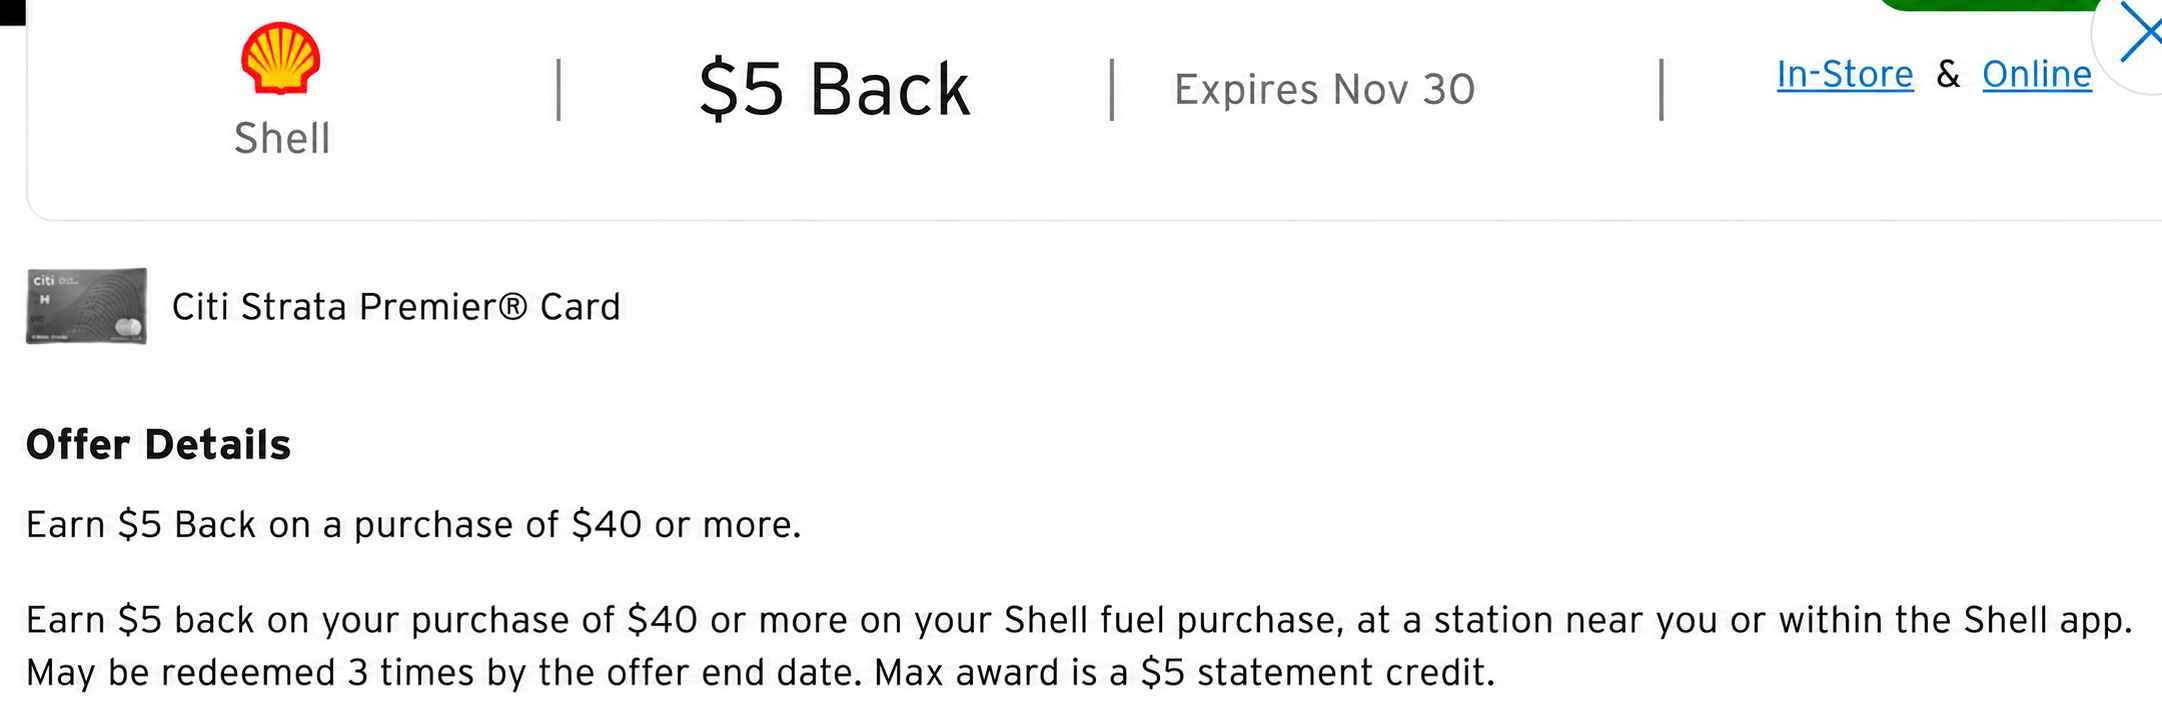
The terms state that the offer may be redeemed three times, giving it a total potential value of $15. In other words, repeatable offers may be worth more than the headline credit suggests.
You may be able to add the same offer to multiple cards
I often notice the same offer on multiple Citi cards in my account. When that happens, you may be able to add and redeem it on each eligible card for double (or more) value.
Rates may also vary by card, such as 5% on one and 10% on another. If you’ll only use the offer once, make sure you activate and pay with the best card for the deal.
How and where you pay may matter
Some offers only apply to specific purchases. For example, I have a Marriott offer on my account right now, but it’s only valid for reservations made directly with Marriott at U.S. properties— no third-party bookings. Other travel offers may require a prepaid reservation.
Also check if the threshold must be met in one transaction and whether taxes, fees or gift cards count.
How to maximize Citi Merchant Offers
Activating an offer is easy but maximizing it requires more planning.
Here are the strategies I use:
- Start with purchases you already intend to make. A statement credit doesn’t save you money if the offer convinces you to buy something unnecessary.
- Compare the total return across your cards. If the same merchant appears on multiple cards, consider the statement credit, category earning rate and purchase protections before enrolling.
- Stay close to the spending threshold. A $5 credit on a $40 purchase is a 13% rebate, but the same $5 credit on a $100 purchase is only 5%. If terms allow, you might want to make multiple small transactions.
- Stack with a shopping portal when the terms allow it. You may be able to earn portal rewards in addition to your merchant offer and your card’s normal rewards.
- Join the merchant’s loyalty program. Restaurant, hotel and online travel agency rewards may provide another layer of value.
- Check regularly. Offers update frequently, so you’ll want to check back for new deals.
This summer, I saved $49 on a Blue Apron box by stacking a $24 Citi Merchant Offer with a $25-off promotional code. I also earned 20 Rakuten points per dollar spent and 2% cash back by paying with my (see rates and fees). Combined, that was a great deal on a purchase that made a hectic week easier.
Related: Everything you need to know about credit card merchant offers
Bottom line
Citi Merchant Offers are an underrated source of ongoing value. One statement credit may be modest, but several strategically chosen offers over the course of a year can meaningfully offset an annual fee or make a no-annual-fee card even more rewarding to keep.
I wouldn’t choose or keep a Citi card solely for Merchant Offers, since the deals are targeted and change frequently. But for existing cardholders, they’re one of the simplest ways to get more value from a card already in your wallet.
Related: How to decide if a credit card’s annual fee is worth paying
Disclaimer : This story is auto aggregated by a computer programme and has not been created or edited by DOWNTHENEWS. Publisher: thepointsguy.com