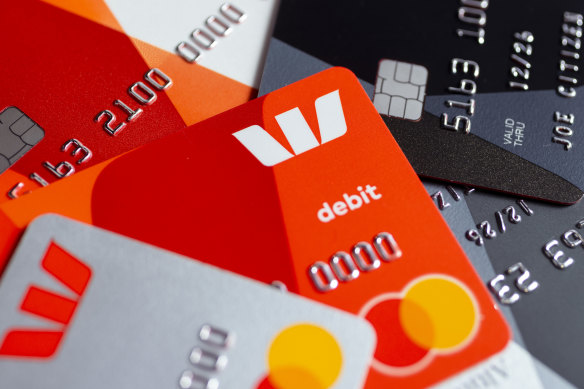
Thanks to the government’s brilliant decision on credit card surcharges and the Reserve Bank acting on it, I’m now going to be charged an extra $75 a year on top of my existing $175 card fee. I’m with BankSA, a subsidiary of Westpac. The bank says the only way to avoid such high fees is to abandon the joint credit card I have with my husband and each get a new card costing $7 a month. That’s $84 a year each, and we would have to apply separately and meet the bank’s lending criteria.
I have never failed to pay the balance in full. We are age pensioners so we may not even qualify. We use debit cards for everyday purchases and the credit card for scheduled bills, travel and emergencies. To cap it off, the supervisor asked whether I really needed a credit card. Is this really how banks now regard older customers who have spent a lifetime paying their bills on time?
This is another unintended consequence of abolishing card surcharges. The cost of processing card payments does not disappear – somebody still pays it. Merchants will try to recover it through higher prices, while banks will look to fees or reduced card benefits. There is a growing argument for using a debit card for everyday spending: you are spending your own money, there is no interest bill and you cannot build up credit card debt. Meanwhile, reward points and other benefits need to be weighed against increasingly hefty annual fees.
For overseas travel, cards such as Wise are also worth investigating.
But credit cards are not redundant. They provide emergency credit, are widely used for hotel and rental-car guarantees, and some offer travel insurance and other protections. For somebody who always pays the balance in full, they remain useful. I would use a debit card for most transactions and keep one low-cost credit card where credit is genuinely useful. Shop around rather than assuming you must stay with your bank. For overseas travel, cards such as Wise are also worth investigating. And I would not be impressed by the bank asking whether you “really need” a credit card. The better question is whether it provides enough value to justify its cost. In your case, perhaps it does – but not at $250 a year.
I have been living and working overseas for a few years but intend to return to my family home in Australia before the six-year absence rule expires, so it should remain covered by the main residence exemption. I have owned it for more than 30 years, so the gain is substantial. I understand that if I sell while a non-resident for tax purposes, I lose the main-residence exemption right back to time of purchase. I have now heard the federal budget changes will deem the property sold on June 30, 2027. If I am still a non-resident then, will I lose the exemption for the entire 30-plus years, even though I was an Australian tax resident for about 90 per cent of that time? This seems extraordinarily retrospective, given I could have sold before leaving Australia without capital gains tax (CGT).
Tax expert Julia Hartman of BAN TACS tells me that is exactly what the second tranche of the draft legislation says. If a non-resident owns Australian real property and has been an Australian tax resident during the ownership period, they will be deemed to have sold it at market value on June 30, 2027, and reacquired it on July 1, 2027. The sting is that if you are a non-resident for tax purposes on June 30, 2027, that deemed sale receives no main-residence exemption for any part of the ownership period.
You could have sold before leaving Australia and paid no CGT, but you reasonably relied on the law as it stood. Whether this is intentional or another unintended consequence of hastily drafted legislation remains to be seen. Your other option is to return and become an Australian tax resident before June 30, 2027. It is also a warning to Australians working overseas: before becoming a non-resident for tax purposes, check whether you can remain an Australian tax resident under TR 2023/1.
I have a will with a testamentary trust. Do I need to redraft it because of the proposed trust tax changes?
Not necessarily, but you should review it. The good news is the government has confirmed testamentary trusts will remain exempt from the proposed 30 per cent minimum tax on discretionary trusts. They remain one of the most effective estate-planning tools, protecting inheritances from divorce, bankruptcy, family disputes and beneficiaries who aren’t ready to handle money, while offering tax benefits. But the exemption isn’t automatic. The trust must be created by your will, the income must come from inherited assets or assets bought with them, and the income must be distributed to an individual or tax-exempt entity such as a charity. The first two conditions are straightforward. The third is uncertain.
A will drawn up 15 years ago may no longer match your circumstances or wishes. Reforms or no reforms, it is worth having it reviewed.
“The government’s own explanation and the legislation itself appear to point in different directions,” says estate-planning lawyer Rachael Rofe. “Until that is resolved, the only safe position is knowing exactly what your will already does.” Most testamentary-trust wills have a wide beneficiary class – children, grandchildren, future grandchildren, spouses, family companies and other family trusts – because nobody knows what a family will look like in 30 years. The legislation seems to focus on who actually receives the income. If so, many existing wills may require no change. But the government’s explanatory material suggests the exemption might apply only where the beneficiary class is limited to individuals and charities from the outset. If so, many wills could require redrafting. We should know soon: “The government wants the legislation passed this year, so anyone reviewing their estate plan today will have a clear answer on whether changes are required as early as October,” says Rofe. Either way, families, assets, relationships and tax laws change. A will drawn up 15 years ago may no longer match your circumstances or wishes. Reforms or no reforms, it is worth having it reviewed.
Noel Whittaker is the author of Retirement Made Simple and other books on personal finance. Email: noel@noelwhittaker.com.au
- Advice given in this article is general in nature and is not intended to influence readers’ decisions about investing or financial products. They should always seek their own professional advice that takes into account their own personal circumstances before making any financial decisions.
Expert tips on how to save, invest and make the most of your money delivered to your inbox every Sunday. Sign up for our Real Money newsletter.
 Noel Whittaker, AM, is the author of Making Money Made Simple and numerous other books on personal finance.Connect via X or email.
From our partners
Disclaimer : This story is auto aggregated by a computer programme and has not been created or edited by DOWNTHENEWS. Publisher: www.smh.com.au