There is a new AI craze taking off, one that could supposedly change everything from choosing a bank account to booking a table at a restaurant.
AI-powered “agents”, which act as a type of digital personal assistant, are surging in popularity, and as with all things AI, there’s a chance this could have major financial ramifications.
For the uninitiated, AI agents are bots to which humans can delegate everyday tasks. You might ask it to book flights or a hotel, do some online shopping, or hunt down a better deal on your insurance.
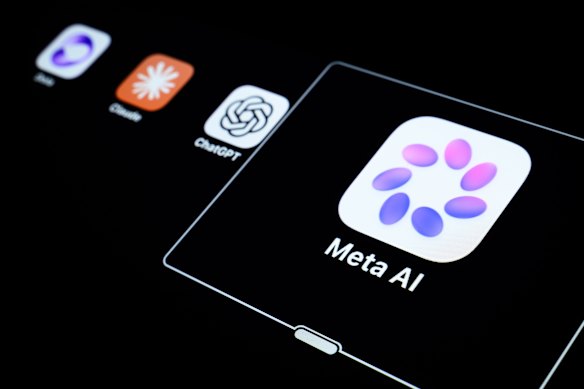
Facebook’s owner, Meta, recently launched a personal agent called Muse, and last week it had skyrocketed up the charts to become the most downloaded free app in the US Apple app store. Meta is making Muse available in smart glasses and a new pocket-sized device called Charm, and its boss, Mark Zuckerberg, has said the company is building devices for “personal superintelligence”.
If consumers really do embrace these tools, which should be good at finding their users better deals online, there will no doubt be losers on the sharemarket, in particular those businesses that make money from consumer inertia.
Some US share prices slumped – in particular those of banks, which benefit handsomely from the fact most of us can’t be bothered shopping regularly for a better home loan or deposit rate because it’s a pain. Travel agency shares were also hit on fears their model is under threat.
So, at first glance, this might look like good news for consumers. Personal finance gurus are constantly advising us to shop around for a better deal for financial services, so what’s not to like about a bot doing it for you?
Unfortunately, however, it’s not that simple. There are plenty of reasons to be sceptical of AI-powered shopper bots.
A personal comparison bot that hunts down the best deals for you while you do something more enjoyable sounds great in theory, but how do you know it really is hunting down the best deal, rather than bowling up offers from the businesses that have paid the bot’s developer a kickback?
How do you know it’s really scanning all the best options that are out there?
And how do you know the bot hasn’t been tricked by, or even colluded with, other bots that have been deployed by businesses trying to sell you their products?
These are questions regulators must consider as hype builds around these sorts of agents, and the issues have also been on the mind of Assistant Minister for Productivity and Competition Andrew Leigh, who unpacked them in a speech a few months ago.
Economists are always interested in how consumers and businesses make decisions in a market, but Leigh pointed out that these agents introduce “a new and unpredictable gatekeeper” when we’re shopping online.
Online shopping has transformed how we buy things, in many ways for the better, but humans have always been in the driving seat – deciding what to search for, clicking on the links that look appealing, and deciding whether to go ahead with a purchase.
What might go wrong as a result of delegating these decisions to a bot? Leigh suggests four examples of possible “agentic misbehaviour” to be alert to.
First, agents could be “steered” towards certain products by financial incentives to recommend one product over another, which may not be obvious to the user. In other words, a kick-back. In some cases today these are banned, and in other cases they must be disclosed. How will you know if the business that created your personal assistant is getting a kick-back for recommending some products over others?
Second, Leigh outlined the risk of prices becoming more “personalised,” raising the risk of buyers being exploited. After all, it won’t just be shoppers using agents to hunt down better deals. Companies will deploy their own bots which will try to convince the shoppers’ bots that they have the best deal.
But as the sellers’ bots find out more about the person buying, they could try to take advantage of the situation. For example, if a whitegoods retailer’s bot can figure out that one customer is calmly researching a fridge, while another customer needs one desperately today because theirs has failed, it may jack up the price for the more urgent buyer.
This is called “price discrimination” in economics, and it’s quite possible the rise of bots could make it more prevalent.
Third, Leigh says sellers’ agents could learn how to game the system so their products appear higher on the internal ranking systems of the buyers’ bots. You might think your AI agent has picked out the best options, but if it’s been gamed, its recommendations will be more like advertising.
Fourth, there’s a risk that bots working for rival businesses could collude to rip off their customers by fixing prices – a danger the consumer watchdog has also highlighted in the past.
Leigh isn’t the only one to have reservations about the rise of agentic shopping. Various banks around the world, including Commonwealth Bank, last week called for some common principles to support the development of “agentic commerce”. The banks highlighted customer concerns about being dudded by agents, and suggested broad principles around transparency, safety, privacy and preserving choice.
Of course banks have plenty of self-interest in fending off threats from the bots, which could well move into banking services.
But even so, the rise of AI-powered shopping agents clearly poses all sorts of risks for consumers, as well as potential benefits. After all, these agents are being created to make money for their creators – they’re not a public service.
As Leigh explains, competition regulators will have plenty of work to do in policing these new products. This might mean conducting their own “mystery shopping” for example, or it might mean looking under the bonnet to see how agents make their recommendations.
None of this means we should ignore the promise of AI to help consumers, whether that’s by saving us time with paperwork, or helping us hunt down a better deal. That’s the hope, Leigh said, but there is also a more pessimistic scenario. “The risk is that agents become a digital version of the charming salesperson who is getting a cash bonus for selling you an extended warranty,” he said.
For all the hype about “personal superintelligence”, there are still plenty of reasons to be sceptical about the rise of AI-powered bots that claim to save you time or money.
The Business Briefing newsletter delivers major stories, exclusive coverage and expert opinion. Sign up to get it every weekday morning.
 Clancy Yeates is deputy business editor. He has covered banking and financial services, and was previously national business correspondent in the Canberra bureau.Connect via X or email.
From our partners
Disclaimer : This story is auto aggregated by a computer programme and has not been created or edited by DOWNTHENEWS. Publisher: www.smh.com.au