Apollo Chief Economic Torsten Slok was on a warpath this past week, issuing a series of warnings about the AI boom as Wall Street retreated from the sector.
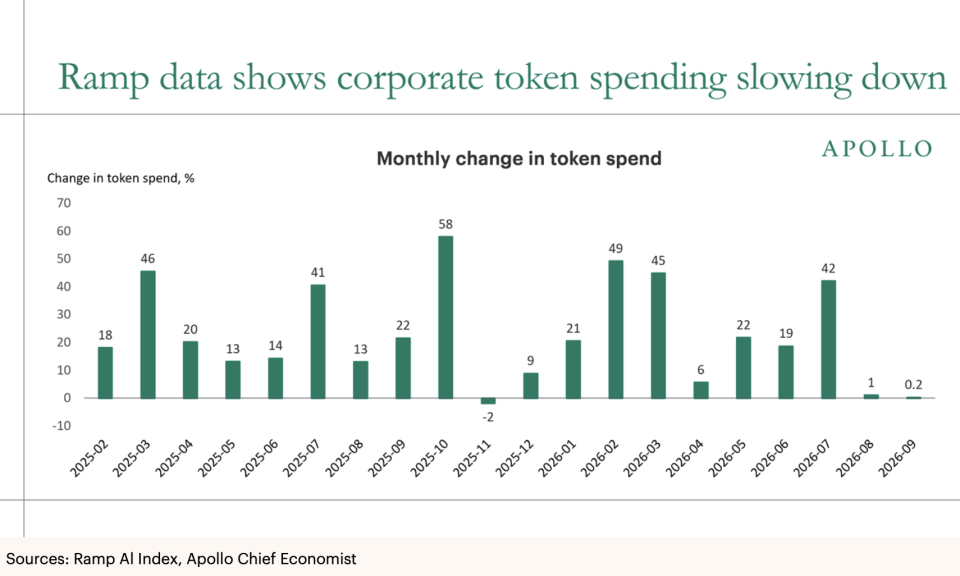
On Tuesday, he pointed to the recent slowdown in token spending growth, saying the demand curve for compute is flat and highly sensitive to price changes.
Meanwhile, most companies that are investing in the technology have yet to see significant productivity returns, Slok added, with AI now looking more like a cost center than a growth driver.
“The core economic flaw in the AI bull case is that the marginal cost of producing compute exceeds the marginal benefit it delivers to users, raising questions about claims of unlimited demand for data centers,” he explained. “How much compute and how many data centers are needed depends on the returns firms are able to generate with that compute. So far, the AI payoff for firms has been slow to materialize, implying a growing reluctance to pay for AI services.”
The main determinant in data-center construction models isn’t physical capacity or power, he argued. Instead, it’s the actual price users are willing to pay for compute.
But companies will only pay a high price if it translates to higher revenue growth, bigger profits, or substantial savings—and there its little sign any of those exist at scale, Slok wrote.
“Maybe that will come in the future. Maybe not,” he warned.
On Thursday, he sounded the alarm on “circularity” in token spending. AI companies have already come under scrutiny for financing deals where they provide money or guarantee debt for other companies that are also top customers, raising doubts about how sustainable their growth is.
Slok suggested a similar dynamic exists between AI startups and the venture capital firms that invest in them, saying 80% of the top 1% of AI spenders are VC-backed. In his view, that means startups are paying for their compute bills with venture capital rather than organic earnings.
And on Saturday, he declared AI has “delivered zero financial payoff” to U.S. companies outside of the big hyperscalers. While profit margins and revenue per workers are rising for the so-called Magnificent Seven, the rest of the S&P 500 has seen no such improvement.
Echoing the week’s earlier notes, Slok said Corporate America overall doesn’t need the latest AI model—and doesn’t want to pay for it. But even as AI becomes cheaper and commoditized, mainstream companies may have a hard time using the technology to boost financial results.
“AI may be a great calculator, but in business, intelligence is mostly judgment,” he wrote. “Judgment depends on context, and the answer varies with which human or which model you ask. Perhaps most importantly, AI does not understand accountability, trust, culture, unwritten rules, ethical trade-offs or fairness, all of which shape reputational risk and ultimately drive revenue growth and profit margins.”
His series of notes came as AI-related stocks tumbled, especially chip names, with traders doubting how much longer the capital expenditure orgy can go on. A handful of hyperscalers plan to spend an estimated $800 billion this year, with capex next year seen topping $1 trillion.
But AI companies may find that raising all that capital won’t be as easy. Meta has already issued a lot of debt, and announced this week the issuance of a new class of shares, in part to help CEO Mark Zuckerberg pay for a possible wealth tax in California.
With the social media giant planning to spend $135 billion-$145 billion this year, the cost of insuring Meta’s debt against default touched a record on Thursday. Five-year credit default swaps widened 7.6 basis points to an all-time high of 114.79 basis points.
At the same time, smaller AI companies like “neoclouds” have come under pressure. For instance, CoreWeave stock has crashed more than 30% this month, and its five-year credit default swaps have shot up to 1,145 basis points.
The worries don’t end there. S&P’s Global Head for Digital Infrastructure Mark Habib flagged “interconnected financing structures” between hyperscalers and data center projects or smaller AI companies.
“It is safe to assume that there is more (debt) out there that we are not seeing,” he said during a roundtable in London, according to Reuters.
“If it’s not reported, then it’s not part of the disclosure by the hyperscalers. Also, if we are not rating the transactions where this liability may accrue, then the fact of the matter is that we might not have the visibility.”
Disclaimer : This story is auto aggregated by a computer programme and has not been created or edited by DOWNTHENEWS. Publisher: fortune.com