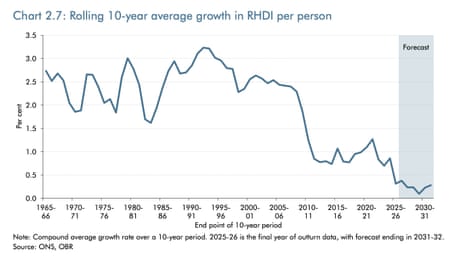
The OBR report says RHDI (real household disposable income – one measure of living standards) is rising at a record slow rate – less than 0.1% per decade. That means, by the end of the decade, it will be just 1% higher than its pre-Covid level, it says.
Our central forecast represents a continuation of the historically weak growth in RHDI per person since the global financial crisis. Chart 2.7 shows the rolling 10-year average annual growth in RHDI per person. This slowed significantly in the aftermath of the financial crisis, due to lower growth in productivity and real wages. Growth reached a historic low over the 10 years to 2025-26, averaging just ¼ per cent a year, and we expect it to fall further in the near term. By 2029-30, our central forecast sees growth over the prior 10 years averaging less than 0.1 per cent a year. As a result, 10 years on from the onset of the pandemic, RHDI per person would be just 1 per cent higher than its pre-pandemic level.
A Treasury minister has dismissed as “garbage” opposition claims that the small print in the budget book shows that John Healey is actually cutting defence spending.
The budget red book says that, while £42.6bn had been set aside for MoD spending in 2027-28, that has now been revised down to £41.1bn.
The Treasury says this is because less money than expected is needed for pensions. But James Cartlidge, the shadow defence secretary, said that not allocating the unused money for other areas of defence spending was “a complete dereliction of duty from the chancellor”.
And James MacClearly, the Lib Dem defence spokesperson, made the same argument. He said:
It is disgraceful that after pitching Labour as serious on defence, Healey and [Wes] Streeting are cutting the military’s resource budget by nearly £1bn next year. This will leave our troops worse off and undermine our security.
In response, Torsten Bell, a Treasury minister, posted this on social media.
Absolute garbage – this is a technical change that happens when public sector pension contributions change. There’s no impact on defence spending power & the Tories used the same mechanism in govt. What does matter for defence spending? The chancellor, who has increased it
Today’s ‘picky bits’ Budget has pushed tough decisions into next year, says Tim Sarson, head of tax policy at KPMG UK:
“When it comes to tax rises, as expected with his options limited by the 2024 manifesto, the Chancellor was left with a pick and mix or ‘picky bits’ approach.
Overall the announcements today will raise £7bn per year by 2031-32 with some winners and losers including a widely trailed bank surcharge which came in lower than expected at 3% and further taxes on the gambling sector
James Smith, ING’s developed markets economist in the UK, says the budget has left more questions than answers.
Those questions include:
How will the government account for higher inflation in departmental budgets? How will it fund defence? Both questions were left unanswered today. The government’s overall spending pot for government departments was left largely unchanged later this decade, despite a higher path for inflation and the Chancellor’s reaffirmed commitment to 3% NATO spending by 2030. Implicitly, that pledge is being funded by squeezing other areas of government; the OBR’s numbers imply real-terms cuts of 2.6% a year for unprotected departments later this decade.
That almost certainly won’t happen – and this is before you take social care or any of Prime Minister Andy Burnham’s other bold policies into account.
These thorny issues have been punted into 2027, potentially in the autumn, when the government will have to unveil its long-awaited Spending Review.
The New Economics Foundation say the Budget is a missed opportunity to bring down inflation, though more ambitious cost of living measures.
They say:
The chancellor has missed an opportunity to bring down inflation rates, according to analysis from the New Economics Foundation (NEF). The research suggests a more ambitious package of cost-of-living policies would take inflation from the OBR’s projected 3.64% to 2.88% by June 2027.
But Capital Economics say the chancellor has done enough to keep the markets on side.
Today’s UK budget announcement has proven the non-event that newly-minted Chancellor Healey had signalled in advance. While his first budget is hardly inspiring, it contrasts favourably with the initial efforts of some of his recent predecessors.
By sticking to a gradual fiscal tightening path, and to the expectations set over the past couple of months for a muddle-through budget, Healey has probably done enough to keep the Gilt market on side for now.
We think that Gilt yields will fall over the coming year as the UK’s fiscal risk premium remains contained and the Bank of England policy takes a less hawkish path than money markets discount.
The government needed to issue a ministerial direction to get UK Export Finance to approve a £3bn increase in lending for Ukraine, it emerged today. This is a procedure that happens when a civil servant judges that a decision is not justified under normal responsible public spending rules, and insists that it can only go ahead if a minister explicitly overrules the objections.
In his letter explaining the need for a ministerial direction, Tim Reid, UKEF’s chief executive, argued that this was not a core obligation for the agency (which is there to help British exporters, not to fight Russia) and that the risk of the £6.5bn not being paid back was too high.
Reid said:
UKEF has played a significant role in delivering the government’s support to Ukraine by staying on cover with £3.5bn of capacity to provide export finance, supporting strategically important transactions including the supply of nuclear fuel, reconstruction of critical infrastructure and air-defence missiles. These have supported Ukraine’s resilience at a critical time while also creating jobs and industrial capacity across the UK.
However, the financial risks associated with UKEF providing support in Ukraine remain far beyond those that we would normally be willing to accept. The probability of default and expected loss is exceptionally high …
UKEF is close to capacity against its existing £3.5bn limit. You have now asked me to consider a £3bn increase in UKEF’s cover limit, taking UKEF’s Ukraine country risk limit to £6.5bn.
In response, Jonathan Reynolds, the business secetary, said he was issuing a ministerial direction because “the United Kingdom has been steadfast in its support for Ukraine’s defence, economic resilience and long-term recovery, and I consider UKEF’s support to be an important component of that wider effort.”
Labour’s Employment Rights Act is likely to have a negative impact on the economy, the OBR says today.
This is the first time that the OBR has assessed the potential economic impacts of the ERA, which received royal assent at the end of last year.
And the fiscal watchdog has concluded the ERA will probably have a negative impact on potential output, though it isn’t making an explicit assessment today.
The OBR says:
Our analysis suggests that the ERA will likely have a negative economic impact from negative impacts on businesses, particularly through increased uncertainty, lost flexibility and higher labour related costs, which will more than offset any potential positive impact on worker productivity.
That fits with the government’s own analysis, which said the reforms could cost businesses up to £5bn a year.
Earlier John Healey got an endorsement for what he said about defence spending from Mark Rutte, the Nato secretary general. (See 2.15pm.)
George Robertson, the former Nato secretary general and the lead author of the strategic defence review, has also welcomed Healey’s defence announcements. (See 1.30pm.) He said:
John Healey is acting in the national interest – and has done exactly what he said was needed for defence in his resignation letter, by setting a headmark for 3% in 2030.”
I am strongly in favour of innovative ways of financing defence – and this is a credible route to get more into UK defence. Today’s annoucements strengthens UK leadership in Nato once again.
In his speech Healey announced an extra £10bn in economic support for Ukraine. This Treasury news release explains where that money is going. It says:
The £10bn package includes £7bn of economic support being made available over three years, including up to £5.5bn of World Bank guarantees and a £500m grant contribution to the World Bank International Development Association’s crisis facility, mobilising £1.5bn of support for Ukraine.
Alongside this, there will be a £3bn increase in UK Export Finance (UKEF) capacity for Ukraine, prioritised for military support. It will bring the total UKEF support to £6.5bn.
Over at Saxo UK, traders report there was little drama in today’s budget.
“It was a boring budget” says Andrew Bresler, the chief executive of Saxo UK, adding:
They have been able to achieve what they set out to which is effectively no movement in financial markets.
Neil Wilson, an investor strategist at the bank, says the budget was “a nothing burger”, pointing out:
The market is not really reacting to it.
Business groups have given the budget a mixed reaction.
Rain Newton-Smith, chief executive of the CBI, welcomed some measures, but argued John Healey should have done more for growth. She said
On the face of it, this budget lacks the bold moves that would have made it easier for firms to invest, hire and grow.
At a time of exceptional geopolitical pressures, using some fiscal headroom to absorb genuine short-term shocks is preferable to loading additional permanent costs onto business and weakening investment.
Slowing the convergence of youth rates with the national living wage is a sensible move in face of the Neets crisis and current labour market pressures. But the chancellor could have gone further. Reducing the cost of hiring by increasing the employer NICs threshold would have given firms more space to create entry-level jobs and boost employment.
Jonathan Geldart, director general at the Institute of Directors, said his members were relieved.
Business leaders will be relieved that the chancellor’s budget included no nasty surprises, having been conditioned in previous budgets to expect the worst. We very much welcome the numerous measures intended to support British start-ups and scale-ups, such as the new Founders’ Relief, Young Entrepreneurs Allowance and EMI2 [enterprise management incentive] share incentives (as well as support for small brewers).
What might at first blush be a case of small beer today could start adding up to something promising in the future.
But Tina McKenzie, national chair of the Federation of Small Businesses (FSB), said the budget was a disappointment.
This budget should have been the moment to help small businesses with the soaring costs holding them back, and the taxes restricting job creation. Instead, they got nothing to ease sky-high energy bills and nothing to make hiring someone more affordable, while the increase in business rates relief excludes too many.
A JP Morgan spokesperson has criticised the decision to hike the UK’s bank tax today, arguing that targeting one of the UK’s most lucrative sectors “lacks principle”:
“We are committed to the country, and we recognise the cost of living challenges there and the global economic headwinds that it faces, but to single out this industry for additional taxes again, one of the UK’s biggest generators of growth and jobs, lacks principle.
“It also overlooks that the banking industry operates in a highly competitive global marketplace.”
But despite the bank’s disappointment, JP Morgan is due to charge ahead with its £3bn new UK HQ, according to a source familiar with the matter.
More in our business live blog.
Kemi Badenoch’s reaction to the budget on behalf of the Conservative party was covered earlier, at 2.11pm. Here is some reaction from other oppostion parties.
The Lib Dem leader, Ed Davey, told MPs that John Healey should have done more to address the problems with Brexit. He said:
I do think this budget will be more defined by Labour’s red lines on Europe and the Conservatives’ Brexit red tape, rather than faster growth.
And at the root of so much of what’s gone wrong in our country – the cost of living crisis, higher taxes, broken public services, empty high streets, the lack of jobs and opportunity – at the root of all of that is the lack of economic growth.
Our economy is being held back. British business is being held back, and it’s been held back above all by the terrible damage of the Conservative Brexit deal.
Ellie Chowns, the Green party Treasury spokesperson, said the budget was lacking in ambition.
You’d have thought that, after going to the trouble of ousting the last PM, taking his job, and installing a brand-new chancellor, Andy Burnham would be keen to ensure Labour displayed a bit more ambition at today’s budget than it did under his predecessor.
Unfortunately, what Britain actually saw today was a business-as-usual budget which failed to engage with the real issues facing our country – choosing to tinker round the edges, rather than properly taxing extreme wealth and profits, making essentials genuinely and permanently affordable, or investing in our long-term climate resilience.
There was no discussion of the climate crisis in Healey’s speech today, nor any new investment in renewables and climate adaptation, despite the devastating impact of this summer’s deadly heatwaves and wildfires on our communities, public services, and economy.
Nigel Farage, the Reform UK leader, said Britain was broke. In a post on social media, he said:
These are the stats John Healey doesn’t want you to read.
Unemployment will rise to 5% in 2027.
The tax burden is going up AGAIN to the highest since WW2.
By 2031 we’ll be spending £160bn/year on debt interest alone – up £36bn/year …
We are on a fiscal knife-edge. Britain is Broke. Britain needs Reform.
Kirsty Blackman, the SNP’s economy spokesperson at Westminster, said this was not a budget for Scotland. She said:
The UK Budget shows the Labour government doesn’t get Scotland – and isn’t doing anywhere near enough to protect people from the looming cost of living emergency this winter.
This isn’t a budget that a Scottish chancellor would have delivered. Instead of providing meaningful help, it has abandoned families in the face of soaring bills and has imposed another betrayal on Scotland’s energy – with the decision to scrap Scottish carbon capture funding.
Andy Burnham promised to cut the cost of living but every major household bill has increased on his watch – and the UK budget completely fails to address the scale of the challenge families are now facing.
Ben Lake, Plaid Cymru’s economic spokeperson at Westminster, said Wales was just an afterthought in the budget.
Today’s budget was UK Labour’s opportunity to prove that Wales is more than an afterthought in Treasury decisions. Instead, it appears to have delivered the worst funding settlement for Wales in years.
After months of promises about a new relationship with Wales and a new approach from the Treasury, the question many people will be asking is – where is the ambition
The chancellor chose not to announce what Wales would receive in consequentials from this budget. Buried in the documents is around £450 million of additional funding spread over three years. That falls well short of keeping pace with inflation and risks forcing the kind of spending reductions Wales experienced during the worst years of Tory cuts.
Machine games duty (MGD) is the tax levied on slot machines found in bookmakers, casinos, bingo halls and adult gaming centres (AGCs). The chancellor faced calls to double the rate of MGD from 20% to 40%, a policy backed by one of his predecessors, Gordon Brown.
Amid fierce lobbying from gambling firms, which issued dire warnings of thousands of job cuts, Healey opted for a more modest rise to 25% today. This, he said, would bring in nearly £150m a year, “raising taxes on gambling to support good growth on every high street”.
Investors responded with relief, adding £240m to the combined stock market value of Entain (Ladbrokes/Coral), Evoke (William Hill), Rank Group (Mecca Bingo/Grosvenor Casinos) and Playtech (designer of slot machine games). Entain said the MGC hike will cost it £25m, which it expects to be able to mitigate, including by shop closures. Betfred boss Fred Done, whose family took a £30m dividend from their betting empire earlier this year, also warned that closures and job losses would follow.
The chancellor singled out AGCs, sometimes known as “slot farms” for particular attention. As well as the duty rise, they will also be excluded – along with vape shops – from business rates relief available to retail and hospitality businesses.
Andy Burnham has ruled out calling a snap general election in the next year amid ongoing speculation (including among economists and investors) that he could seek to consolidate his position.
He said he was thinking “about people” and not “my own party and its prospects”, Press Association reports.
The prime minister was asked if he would call an election in the next year as he visited a community centre in central London after the Budget.
He said:
“I don’t know how many times I’ve done this now, but yes, I can rule out calling a general election in the next 12 months.
“I have said repeatedly since coming into this job, I’m not thinking about myself. I’m not thinking about my own party and its prospects.
“I am thinking about people, and I’m thinking about what I can do to help them to have that care for people, which I spoke about on my first day in Downing Street.”
He added that he was “leading from the front” and “putting Britain on a different path”.
He said:
“We’ve got a 10-year plan to come, and that will inform the spending review next year. These are my priorities, not looking at our own internal party political advantage.”
Several City economists are suggesting that today’s budget may be teeing up an early general election.
Andrew Wishart, senior UK economist at Berenberg, suggests there is a 40% chance of a general election before the end of 2027.
He points out that this would allow Labour to discard its previous manifesto commitments not to raise taxes on working people.
Wishart says:
The big questions, about how to fund a national social care service and a £15bn increase in defence spending by 2030 remain unanswered. The government will hope that the combination of a decline in gilt yields a reduction in transfer payments to those with disabilities and efficiency savings enable them to fund their priorities without a major increase in taxes. It’s just about possible, but pretty unlikely and requires tax hikes pencilled in for the back end of the parliament to come in, potentially just before the next general election.
More ambition would require a new mandate without the manifesto constraint on tax, achieved by via a general election. We put the chances of one before the end of next year at about 40%.”
Eoin O’Callaghan, macro strategist at Wellington Management, says there is a “significant question mark” over the credibility of the projections, including the biig squeeze on departmental spending in a few year’s time.
Like last autumn’s budget they incorporate an unrealistic real term freeze in departmental spending in 2029-30, after the next election. And they now incorporate an even more challenging 3% real terms cut to next year’s departmental spending too to help offset rising interest rate and unfunded public sector pensions costs. The forecasts are also predicated on nominal growth staying relatively elevated close to 4% throughout the forecast.
“That may not concern the market for now. But it highlights how challenging the UK public finances are. How difficult the fiscal decisions ahead of this government are. And why there is a risk of early elections given the tough spending decisions ahead.”
Benjamin Jones, Invesco’s Global Head of Research, predicts speculation about an early election will continue to build:
“After two blockbuster, tax-hiking budgets, investors will welcome this more ‘steady as she goes’ package from the new Labour Chancellor. Against a backdrop of rising gilt yields and geopolitical uncertainty, Healey’s decision to limit spending increases and tax rises shows sensible caution.
His opening comments were clearly aimed to ease bond market fears. However, many of the difficult fiscal choices – such as delivering welfare savings and boosting Defence spending – have been postponed until the Spending Review next year, which will continue to fuel speculation of an early election.
John Healey announced a first-time buyer ISA in his speech. This is what the Treasury says about how it will work.
The government will introduce a new FTB ISA from April 2029. The product will replace the Lifetime ISA (LISA) for new savers and provide a 25% government bonus, paid on withdrawal, towards the purchase of a first home worth up to £450,000. The maximum value of the bonus will be capped at £20,000. Existing LISA holders will be able to continue contributing to and using their accounts under the current rules. In addition, the government will reduce the withdrawal charge for existing LISA holders who use their savings to purchase a first home above the £450,000 property price cap.
Disclaimer : This story is auto aggregated by a computer programme and has not been created or edited by DOWNTHENEWS. Publisher: theguardian.com