US central bank holds interest rates steady ahead of midterm elections – here’s what that means
-
Published
The US Federal Reserve has held interest rates steady at 3.75% – 4%.
The decision comes within a week of the midterm elections and after the central bank raised interest rates for the first time in three years at its September meeting.
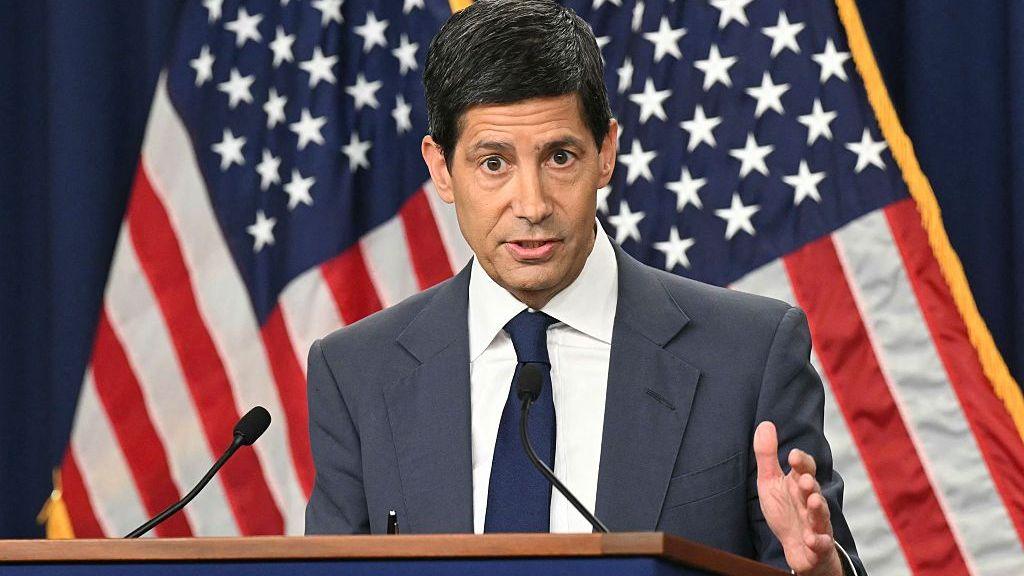
“The overwhelming consensus, the overwhelming judgement, is that what we’ve done in this monetary medicine is starting to work some,” Fed Chair Kevin Warsh said, referring to September’s interest rate rise.
What is the Federal Reserve rate?
An interest rate tells people and businesses how much it costs to borrow money – such as with credit cards, mortgages, or business loans – but also what return they get for saving cash.
The Fed influences interest rates in the US through its target range for the federal funds rate, which is the interest rate used by commercial banks for overnight borrowing.
What’s happening with US interest rates?
In its decision to hold rates steady this month, the Fed said that while inflation remains high, it wanted to gather more information before making another decision to change rates.
The Fed also noted that while there was uncertainty, the US economy remained resilient.
Warsh acknowledged that inflation remained too high, but noted that there were other signs – such as tightening credit conditions – that the economy was moving in the right direction.
There is plenty more economic data to come between now and the committee’s next meeting, the Fed chair added, which should paint a more detailed picture of the state of the economy.
At that point, Warsh said, “we’ll be, I think, better positioned to determine the right policy decision and the stance of policy.”
While last month the committee signalled there could be one more rate rise this year, Warsh would not be drawn out on where he thinks they will go in six weeks’ time.
“A lot of things can happen, so I’m not going to be able to share with you my musings.”
The decision to hold rates steady was not unanimous.
While 10 of the 12 committee members voted to keep rates unchanged, Governor Lisa Cook and Cleveland Fed President Beth Hammack voted to increase rates to 4%-4.25%, from its current 3.75%-4%.
The bank’s next meeting will be held over 8-9 December.

How does the Fed rate affect mortgages, credit cards, and savings?
The Fed uses interest rate changes to try to keep inflation – the rate at which prices change – at 2% a year and keep the job market stable.
When inflation is too high, the Fed tends to raise interest rates.
This tends to mean higher rates from banks and other lenders, which in turn affects spending and saving decisions.
For example, someone refinancing their mortgage or buying a property for the first time could face higher mortgage rates. It could also mean higher interest rates on credit cards or car loans. However, it means higher interest rates on savings as well.
This encourages people and businesses to save more, spend less money, and make less investments. It also encourages companies to hire less people or slow the pace of pay rises.
All of this tends to reduce demand and slow inflation.
When inflation is low or if the Fed believes the economy needs a boost, it cut rates.
The idea is that this will have the opposite affect, with banks dropping rates leading to more spending and less saving from people and businesses.
Leaving the rates unchanged means rates on things like new mortgages or business loans are also less likely to change. It also means interest rates on cash savings are unlikely to rise.
How much have US interest rates changed?
US interest rates have historically moved around quite a bit.
The last time Fed rates were as high as they have been recently was in the lead up to and during the start of the 2008 global financial crisis.
The Fed then dropped rates to historic lows to encourage spending and job creation during the economic slump and kept them at those lows for several years.
They picked up again ahead of the pandemic before dropping to as low as 0%-0.25% during the pandemic. They then rose to highs of 5.25%-5% from the middle of 2023 to August 2024 as inflation jumped.
They had been falling steadily since then, until rates were raised last month.
-
-
Published14 October

-
-
-
Published1 day ago

-
Disclaimer : This story is auto aggregated by a computer programme and has not been created or edited by DOWNTHENEWS. Publisher: BBC