TOKYO –
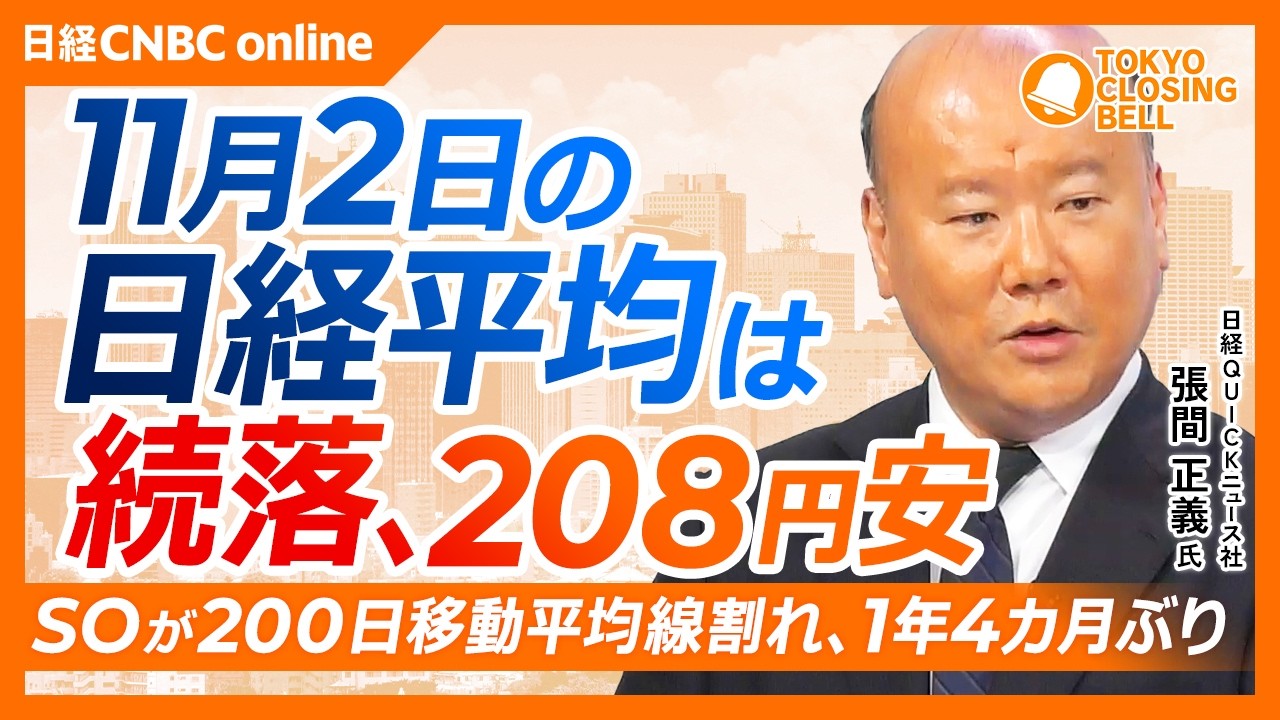
Japan’s benchmark Nikkei 225 Stock Average fell 208.25 points, or 0.33%, to close at 63,081.86 at 3:30 p.m. on November 2, extending its losses for a second consecutive trading session as a sharp decline in memory chipmaker Kioxia Holdings and continued uncertainty over US technology stocks outweighed gains in semiconductor equipment manufacturers.
The broader TOPIX index dropped 34.79 points, or 0.88%, to 3,930.28, reflecting widespread selling across the Tokyo Stock Exchange. Trading was relatively active, with turnover on the Prime Market reaching approximately 7.64 trillion yen on volume of 2.33 billion shares. Declining stocks substantially outnumbered advancing issues, underscoring the weakness beneath the Nikkei’s comparatively modest decline.
Tokyo shares opened sharply lower following heavy losses on Wall Street on October 30, when selling in technology and semiconductor stocks unsettled global investors. The Nikkei initially fell more than 570 points to an intraday low of 62,712.91 before recovering during the morning and briefly moving into positive territory in the afternoon. However, buying momentum faded toward the close as investors reduced exposure ahead of a national holiday.
Kioxia Holdings was among the day’s biggest casualties, plunging 15.78%, or 2,125 yen, to 11,345 yen after its latest financial results and outlook disappointed investors. The company had forecast relatively flat sales for the October-December quarter, raising concerns that earnings growth may struggle to match expectations despite strong demand for memory chips associated with artificial intelligence and data centers.
The stock’s decline alone reduced the Nikkei by approximately 150 points. Recruit Holdings, SCREEN Holdings, SoftBank Group and Kyocera also weighed heavily on the index, indicating that the selling extended beyond memory chip producers.
Other semiconductor-related companies performed considerably better. Tokyo Electron gained 5.16% to 10,005 yen after reporting favorable earnings and announcing a share buyback program worth up to 150 billion yen. Advantest and Lasertec also advanced, helping offset losses elsewhere in the technology sector. Tokyo Electron contributed approximately 248 points to the Nikkei’s performance, while Advantest added another 196 points.
The contrasting performances highlighted increasing selectivity among investors toward Japanese semiconductor companies. While expectations of continued global investment in artificial intelligence remain substantial, financial results are receiving closer scrutiny as investors question whether earnings can justify elevated valuations.
Across the Tokyo market’s 33 industry groups, only 10 registered gains. Glass and ceramics, food producers, electric utilities and railway operators were among the stronger sectors, while warehousing and transportation services, precision instruments and service companies recorded significant losses.
The foreign exchange market added another source of uncertainty. The yen weakened modestly against the dollar, trading at around 157.78 yen at 3:42 p.m. in Tokyo, compared with approximately 157.56 yen at the previous New York close. The dollar briefly climbed to 157.99 yen before encountering resistance near the psychologically important 158-yen level.
The softer currency continued to present mixed implications for Japanese businesses. Export-oriented manufacturers generally benefit from a weaker yen when overseas earnings are converted into Japanese currency, but import-dependent industries face higher costs for energy, raw materials and other goods. The benchmark 10-year Japanese government bond yield stood at approximately 2.77%, highlighting the elevated borrowing costs confronting businesses and households.
Economic data released on November 2 showed that Japan’s manufacturing sector continued expanding in October, although growth slowed as new orders lost momentum and input costs increased. The S&P Global Japan Manufacturing Purchasing Managers’ Index declined to 53.3 from 54.1 in September, remaining above the 50-point threshold separating expansion from contraction but recording its weakest reading in seven months.
Factory output increased for a 10th consecutive month, supported by semiconductor demand and improving order volumes, although the pace of expansion was the slowest since March. New orders also rose for the 10th straight month, but their growth moderated as manufacturers reported less vigorous demand from some customers.
Export orders continued to increase, with companies identifying business opportunities in China, other Asian markets, North America, Africa and the Middle East. However, overseas order growth was also the weakest since March, suggesting that Japan’s export recovery may be entering a more moderate phase.
Employment conditions remained comparatively favorable, with manufacturers continuing to recruit workers at a pace close to the fastest recorded in more than eight years. Business confidence about the coming 12 months improved to an eight-month high, helped by expectations surrounding artificial intelligence, new product launches and opportunities to secure additional customers.
Nevertheless, rising purchasing costs posed a growing challenge. Input price inflation accelerated in October, while the rate at which manufacturers raised their selling prices slowed to a six-month low, indicating potential pressure on profit margins. Companies also increased their inventories of purchased materials at the fastest pace in nearly four years as they sought protection against further price increases and potential supply disruptions.
Corporate earnings announcements provided further evidence of the contrasting fortunes facing Japanese businesses.
Japan Airlines reported an 11.7% increase in revenue to approximately 1.099 trillion yen for the six months ended September 30, marking its highest first-half revenue since returning to the stock market. However, net profit fell 42.2% to approximately 39.1 billion yen as higher fuel prices and the weak yen sharply increased operating expenses.
The airline’s fuel costs rose 47.4% from a year earlier to approximately 285.6 billion yen, outweighing improvements in international passenger revenue, cargo demand and domestic ticket yields. Earnings before interest and taxes declined 36% to 70.1 billion yen. Despite the profit decline, Japan Airlines maintained its full-year forecast of 180 billion yen in EBIT and 110 billion yen in net profit, reflecting expectations of continued demand for air travel during the remainder of the fiscal year.
Trading house Sumitomo Corporation delivered a stronger earnings performance, reporting a 15.5% increase in net profit to approximately 347.9 billion yen for the April-September period. Revenue rose 10.8% to approximately 3.92 trillion yen, supporting an upward revision to the company’s full-year earnings forecast.
Sumitomo raised its projected annual net profit from 630 billion yen to 670 billion yen, an increase of 6.3%, putting the group on course for another record annual result. The company also increased its planned annual dividend from 40 yen to 44 yen per share, adjusted for its four-for-one stock split earlier in the year.
Sumitomo Chemical likewise announced an improved earnings outlook. Net profit for the first six months more than doubled from a year earlier to approximately 82.8 billion yen, exceeding the company’s previous forecast of 70 billion yen. The chemical producer raised its full-year net profit projection by 28.6% to 90 billion yen and increased its planned annual dividend from 16 yen to 17 yen per share.
The improvement came despite persistent challenges in the chemicals industry, where volatile raw material prices, international competition and changes in industrial demand continue to influence profitability.
Electronics and materials manufacturer Kyocera reported an 8.8% increase in first-half revenue to approximately 1.078 trillion yen, while operating profit jumped 56.4% to 65.6 billion yen. Net profit rose 32.2% to approximately 73.4 billion yen.
However, Kyocera’s July-September quarterly net profit fell about 30% from a year earlier, suggesting that the strong first-half performance masked a deterioration in more recent operating conditions. The company retained its full-year net profit forecast of 160 billion yen.
The earnings announcements highlighted the uneven impact of Japan’s economic environment. Trading companies and selected manufacturers continued to benefit from stronger business operations, while airlines and other businesses exposed to fuel costs faced substantial pressure despite rising sales.
Investors are now preparing for a particularly busy week of corporate earnings. More than 500 listed companies are scheduled to release financial results between November 2 and November 6, with major announcements expected from Toyota Motor, Sony Group, Nintendo, Mitsubishi Heavy Industries and leading trading houses.
Toyota and Sony are among the companies expected to report on November 5, providing important indications of global consumer demand, currency movements and the resilience of Japan’s automotive and electronics industries. Mitsubishi Heavy Industries is scheduled to report on November 6, with investors watching developments in defense, energy systems and industrial equipment.
The international economic outlook will also remain an important influence. Investors are monitoring developments in US monetary policy, global technology shares, oil prices and the November 3 US midterm elections. Questions about the profitability of large-scale artificial intelligence investment have increasingly shaped technology-sector valuations, making earnings forecasts and capital spending plans particularly important.
Japanese financial markets will be closed on Tuesday, November 3, for the Culture Day national holiday, with regular trading resuming on Wednesday, November 4. The interruption comes at a sensitive moment for global equities, leaving Japanese investors exposed to developments in overseas markets before domestic trading resumes.
For the remainder of the week, attention will focus on whether the Nikkei can stabilize above 63,000, whether the yen weakens beyond 158 per dollar, and whether forthcoming corporate results provide sufficient support for Japanese equities following the latest bout of semiconductor-led selling.
Disclaimer : This story is auto aggregated by a computer programme and has not been created or edited by DOWNTHENEWS. Publisher: newsonjapan.com