Roger Bootle
You may think you have lived through an enormous economic shock as the result of the rise of China and surging Chinese exports. But you ain’t seen nothing yet.
It was widely believed that before too long, China’s export share would stabilise. Yet nothing of the sort has happened. Indeed, the world faces a second phase of the China shock, which is known in the trade as the China Shock 2.0.
From 2010 to 2018, when President Trump introduced the first round of tariffs against China, Beijing’s share of world goods export volumes rose from just over 9 per cent to nearly 13 per cent. In late 2021, it plateaued has since surged again and currently stands just short of 19 per cent.
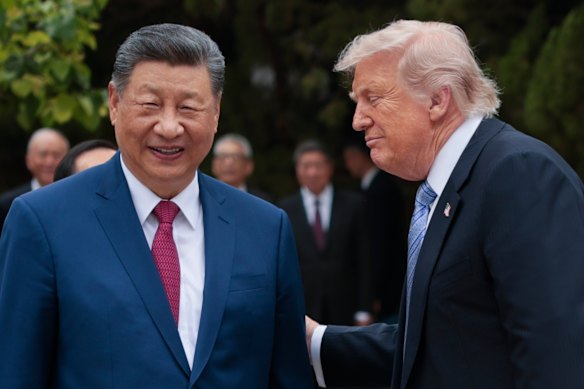
Remarkably, Trump’s second round of tariffs against China, launched after he became president again in January 2025, has had next to no impact on this upward surge, even though it has had an impact on China’s trade with the US. But this has simply led to a redirection of China’s exports to other parts of the world, and those other parts have stepped up their exports to the US. Over the last year, in dollar terms, China’s exports to the rest of the world are up by about 25 per cent.
What is behind this surge in Chinese exports? First, there is the impact of sustained investment by Chinese firms, pretty much across the board, including the widespread use of robots to improve productivity in labour-intensive industries. China invests about 40 per cent of its GDP, an enormous figure by Western standards.
Admittedly, it has invested this much for many years, but the difference now is that, whereas in the first phase of China’s development it pushed a lot of investment into real estate, since the real estate crash this has been diverted into manufacturing.
Meanwhile, China’s domestic demand has been weak. The growth of consumers’ real incomes has faded and the housing market has been extremely soft, with house prices having fallen by about 20 per cent. This is particularly important since housing makes up about a half of consumers’ wealth. The result is a major drop in consumer confidence as Chinese people tighten their purse strings. Saving was already high, but the savings ratio has risen recently.
This combination of rapidly increasing productive capacity and weak domestic demand has meant that, over recent years, Chinese manufacturers have engaged in price wars. Since early 2023, while goods export prices from the rest of the world have risen by more than 10 per cent, China’s goods export prices have fallen by about 7 per cent.
Scarce wonder, then, that China’s exports have been so competitive in world markets.
Moreover, since the beginning of the first China Shock in the early 2000s, China’s productive capacity and competitive edge have been retained as its output has dramatically climbed the value chain. It has moved into areas of production in which Western countries thought they would hold on to a comparative advantage, enabling them to out-compete China in domestic and world markets.
The effects have been particularly keenly felt in Europe, where traditional manufacturing industries have come under painful competitive pressure. Whereas after the initial China Shock in the early 2000s, Germany enjoyed a surge in exports to China, its exports there have had recent steeps falls.
Meanwhile, Chinese penetration of European markets continues to rise. In 2000, European imports from China amounted to less than 1 per cent of Europe’s GDP. In 2025, the figure was nearly 3 per cent.
What will the consequences be? First, Chinese trade and current account surpluses with the rest of the world which have surged are likely to remain extremely high. Most recently, the Chinese surplus has been running at about 1 per cent of world GDP. These surpluses imply that China’s holdings of overseas assets will continue to rise.
Meanwhile, those countries with a close overlap in productive capacity to China, such as Germany, Poland and Italy, will continue to find life difficult. Interestingly, the overlap between the UK’s productive capacity and China’s is relatively low, and Britain is set to be one of the countries that suffer least from China’s increasing dominance in world markets while continuing to benefit from the lower prices of manufacturing that it entails.
The leadership is broadly happy with the outcome.
You might well imagine that this fantastic export success betokens a massive advance for the Chinese economy. But it doesn’t. In many ways, quite the reverse. While China’s share of global manufacturing is pushing up to about one-third as productivity growth has slowed and the consumer economy has languished, China’s share of world GDP has recently fallen. Remarkably, something like a third of Chinese firms are loss-making and 4.4 per cent of China’s GDP is spent on industrial subsidies.
Not that this implies that things have to change radically any time soon. As Capital Economics has emphasised in its recent extended study of the China Shock 2.0, the current state of the Chinese economy is the deliberate result of policies undertaken by Beijing. And the leadership is broadly happy with the outcome.
They do not seek to maximise the economic welfare of the populace in the way that Adam Smith and subsequent economists would have understood. The leadership’s top priorities are technological development, domestic self-sufficiency and geopolitical influence.
Consequently, an important implication of the China Shock 2.0 is the boost it will give to populist political parties across the West and the related erosion of support for the open world trading system which has been behind so much of the world’s increase in prosperity over the past 50 years.
As if the war between Russia and Ukraine and the conflict between America and Iran were not enough, investors need to grapple with the likelihood, at some point, of a bust-up in the world’s trading system, which could be combined with an associated financial shock. In the words of Irving Berlin’s famous song: “There may be trouble ahead.”
Telegraph, London
The Business Briefing newsletter delivers major stories, exclusive coverage and expert opinion. Sign up to get it every weekday morning.
From our partners
Disclaimer : This story is auto aggregated by a computer programme and has not been created or edited by DOWNTHENEWS. Publisher: www.smh.com.au