From building an emergency fund to avoiding the trap of certain rigid pension products, advisor Sebastian Urban lays out the ultimate Day-1 investment roadmap for foreign professionals in Germany.
If you’ve settled in Germany, have a steady income and plan to stick around for years to come – well first of all congrats on taking a solid step toward achieving the German dream!
Among the next major to-dos, however, may be figuring out how to invest some of your savings.
Between complex tax rules, unfamiliar pension schemes and endless investment options, navigating Germany’s financial landscape can be daunting. And crucially, the basic advice that applies to Germans does not always work for foreigners.
The Local spoke with Sebastian Urban, a financial planner and investment advisor, to ask about the advice that foreigners in Germany need to hear as they plan for the future.
Urban’s top takeaway: Successful investing isn’t about cleverly picking the best stocks or nailing complex financial acrobatics – instead he emphasises the importance of following a clear and simple financial roadmap. For foreign nationals in particular this includes making sure to maintain some international flexibility.
Define your goals before picking your investments
Urban emphasises the importance of defining your specific goals before putting a single euro into the market.
“Think about what that money should do for you,” he says. “Why do you want to save…Is it saving for retirement? Or sabbatical in three years, or buying a car, or buying a home…that is a really decisive question, because it determines which investment options are suitable in the first place.”
Focus on the plan, not individual investments
After you’ve got your goals clarified, you can start to formulate an investment plan.
“Keep it simple” is the top tip here.
Urban told The Local that he’s constantly advising his clients to spend more time thinking about their overall financial plan, and less time picking specific investments.
“Thinking about how much you can allocate towards growth-oriented assets like equities…if you maximise allocation there, that’s making a difference…You want to maybe optimise your expenses, so you have more money available to invest. And you probably also want to focus on your human capital, [or] your ability to earn additional income.”
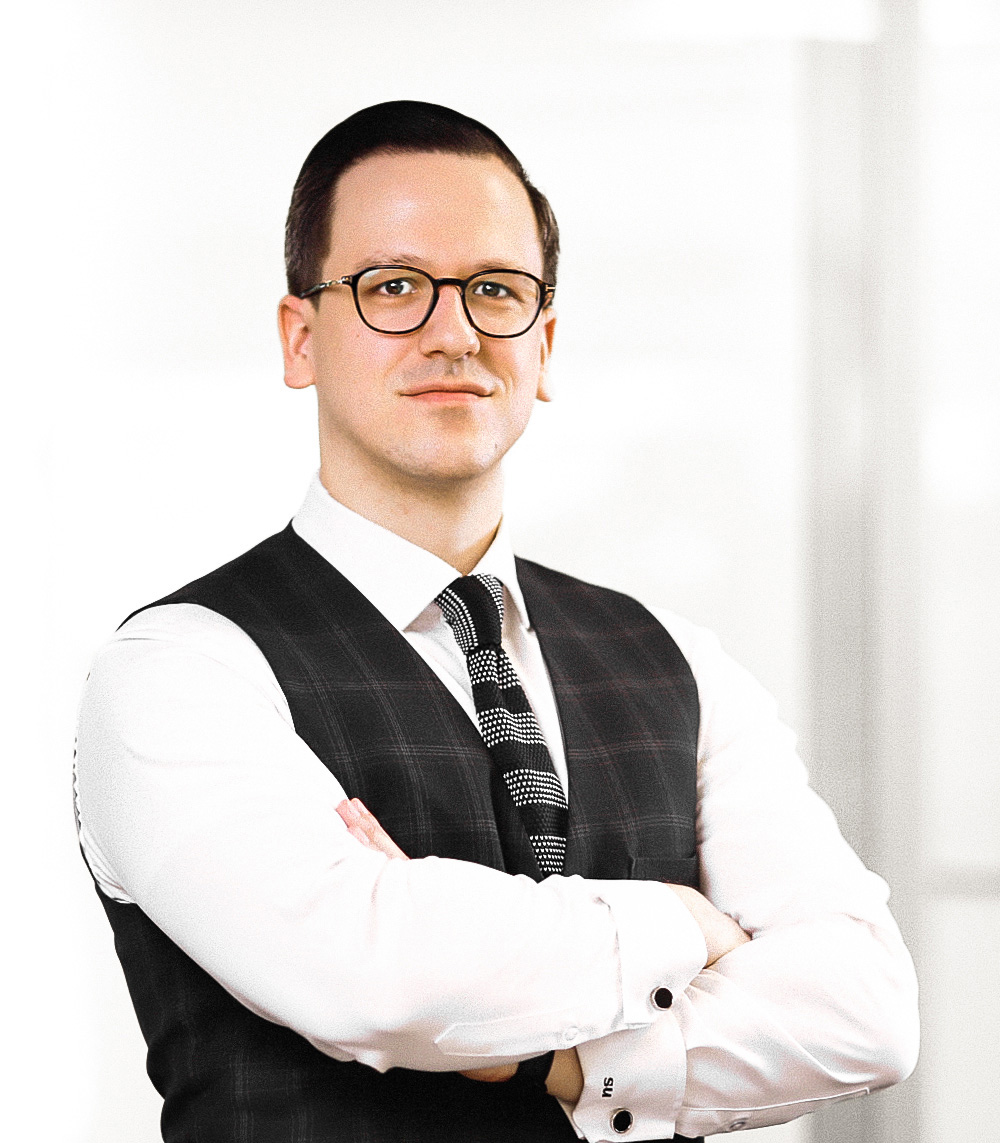
Portrait of Sebastian Urban. Photo provided by Urban.
Know the priority ladder
To make your plan more effective, Urban emphasises the importance of knowing and adhering to your priorities i.e. paying off debt first, building a financial safety net, and then applying the rest toward investments meant to grow over time.
“You want to have a good idea of what you’re earning and what you’re spending…You want to know what you owe,” Urban explains.
Then you can apply a simple hierarchy:
“First, buy off any expensive debt. That’s something you want to get rid of. If you’re paying like 20 percent credit card rates, which happens, paying down that consumer debt gives you a risk-free and tax-free 20 percent return…definitely do that first.”
EXPLAINED: The consequences you face in Germany if you don’t pay debts
After that he advises building up a rainy day fund.
“I would always use the expenses that you have, and then apply a multiple, like three to six months, depending on how secure your job is…That prevents you from going into consumer debt when there is an issue,” Urban says.
Looking forward, the basic advice is that money being saved for a purchase in a few months to years is best kept in a high-interest savings account.
Finally, regarding saving toward retirement, “that’s a question that has actually been answered,” says Urban. “The key is to stay broadly invested, minimise cost, and then just buy and hold.”
The classic example of this would be buying a global, low-cost index fund in the form of an ETF.
Common traps for foreigners in Germany
Most of the above guidance applies well for just about everyone, but for foreign nationals living in Germany, Urban suggests there are a few key things to consider – and traps to be avoided.
For most, living abroad comes with a higher likelihood of moving again in the future, whether that’s back to your home country or onward towards another destination. Whatever the reason may be, unless you’re absolutely certain that you plan to stay in Germany for the rest of your life, you’d be advised to find investment options that fit that contingency.
READ ALSO: DAX hits record high – What you need to know about investing in German index funds
“If leaving Germany is in the cards…you want something that is mobile,” says Urban, adding that you’ll want the option to either take it with you, or else close it out and move the capital to another country.
You don’t want to be stuck with a product that has been designed specifically for the German system.
“So the sort of go-to solution really is sticking to a plain vanilla investment account. A brokerage account with ETFs, or low cost index funds are a good starting point…because you can transfer that stuff. It moves with you,” he explains.
Regarding things to watch out for, Urban says he generally advises his non-German, or more mobile clients against retirement products, which can make things complicated.
“They are always designed for the German system,” he says.
This means that if you should leave Germany in future questions come up around how a particular product is treated in another country, creating financial risks.
The same advice applies to most company pension schemes, which are typically designed to stay in the country.
For certain groups, like US citizens for example, there may be more complicated taxation rules to be aware of that can further complicate your options.
So it’s good to do a bit of research, and/or seek advice from an expert who understands both the German system as well as rules that apply in your home country before setting up major investments.
READ ALSO: ‘I store cash at home’ – Why Americans in Germany struggle to save for retirement
Disclaimer : This story is auto aggregated by a computer programme and has not been created or edited by DOWNTHENEWS. Publisher: thelocal.de