Baron Capital, an investment management company, released its Q2 2026 letter for the “Baron Real Estate Income Fund.” The Fund gained 12.18% (Institutional Shares) during the quarter, modestly outperforming the MSCI US REIT Index, which increased 11.84%. The letter can be downloaded here. Its long-term performance also remains strong, with Morningstar ranking it the #2 real estate fund since its December 2017 inception. The letter discusses management’s current views, portfolio composition, key contributors and detractors, recent activity, and the outlook for real estate and the Fund. Management believes a multi-year recovery in real estate is beginning to emerge, despite elevated interest rates, housing affordability pressures, and AI-related disruption. Its constructive outlook is supported by attractive valuations, accelerating M&A, favorable supply-demand dynamics, healthy balance sheets, improving debt conditions, and increasing recognition of real estate as an AI beneficiary. The Fund remains positioned to benefit from improving growth, rising dividends, and potential valuation normalization. Please review the Fund’s top five holdings to gain insights into their key selections for 2026.
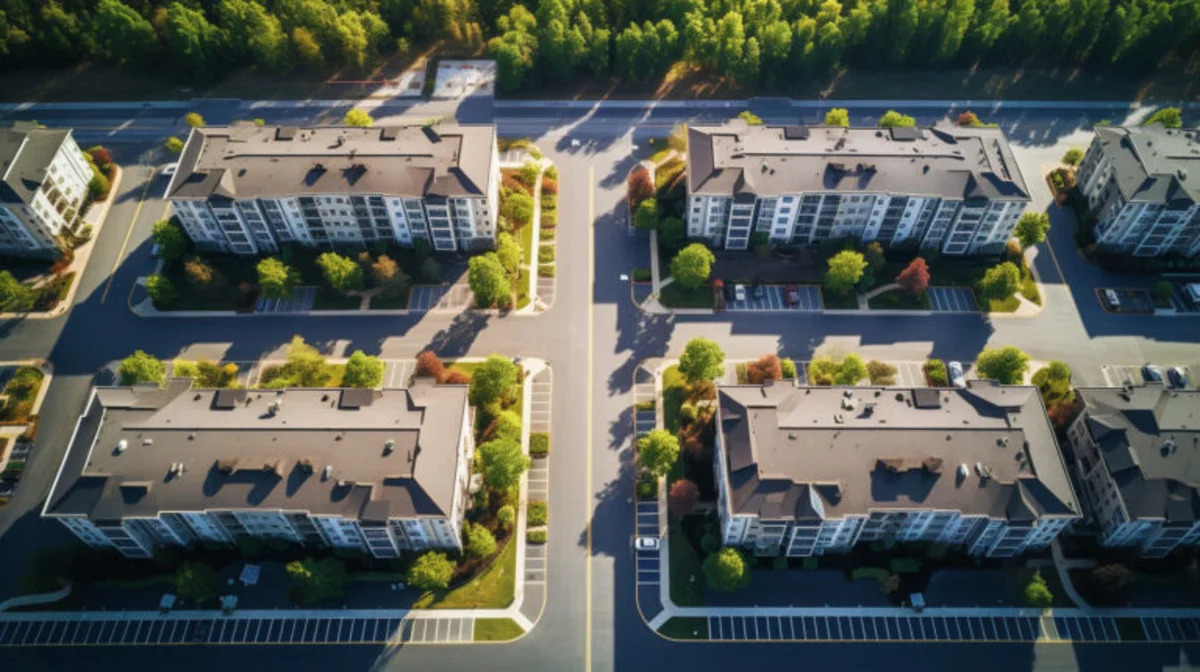
In its second-quarter 2026 investor letter, Baron Real Estate Income Fund highlighted UDR, Inc. (NYSE:UDR). UDR, Inc. (NYSE:UDR) is a leading multifamily real estate investment trust with a demonstrated performance history of delivering superior and dependable returns by successfully managing, buying, selling, developing and redeveloping attractive real estate properties. On September 21, 2026, UDR, Inc. (NYSE:UDR) closed at $33.89 per share. Over the past month, UDR, Inc. (NYSE:UDR) declined 11.21% while its shares lost 9.65% over the past 52 weeks. UDR, Inc. (NYSE:UDR) has a market capitalization of $17.7 billion with a 52-week trading range between $32.94 and $42.00.
Baron Real Estate Income Fund stated the following regarding UDR, Inc. (NYSE:UDR) in its Q2 2026 investor letter:
“In the second quarter of 2026, we increased exposure to multi-family REITs Equity Residential, Essex Property Trust, Inc., and UDR, Inc. (NYSE:UDR). While multi-family REITs have been “cheap” for some time, we are finally seeing early signs of an improvement in business fundamentals that could continue over the next several years given the highly favorable supply/ demand backdrop combined with strong growth in “laggard markets” such as San Francisco. In 2025, we maintained a cautious view on multi-family REITs due to modest near-term growth prospects, influenced by factors such as job losses, younger renters opting to stay at home or “double up,” and elevated apartment inventory. Though we had been cautious, we have become more constructive on multi-family REITs supported by rental affordability versus for-sale housing (with move-outs to purchase remaining at historic lows), a favorable supply outlook through 2027, partial inflation hedging through annual leases, strong rent-to-income ratios among employed renters, and attractive public market valuations relative to private markets and other REIT categories.”
Disclaimer : This story is auto aggregated by a computer programme and has not been created or edited by DOWNTHENEWS. Publisher: finance.yahoo.com