‘My mortgage is going up £200’: How rising interest rates are hitting people’s pockets
-
Published
On Thursday, the Bank of England increased interest rates for the first time in over three years as it tries to get a grip on rising inflation linked to the Iran war.
Experts say there could be more hikes over the next 18 months, as the conflict continues to push up food, fuel and energy prices across the UK and worldwide.
Higher interest rates affect borrowing costs, however, which means mortgages, credit cards and personal loans could get more expensive for millions, even as savings rates improve.
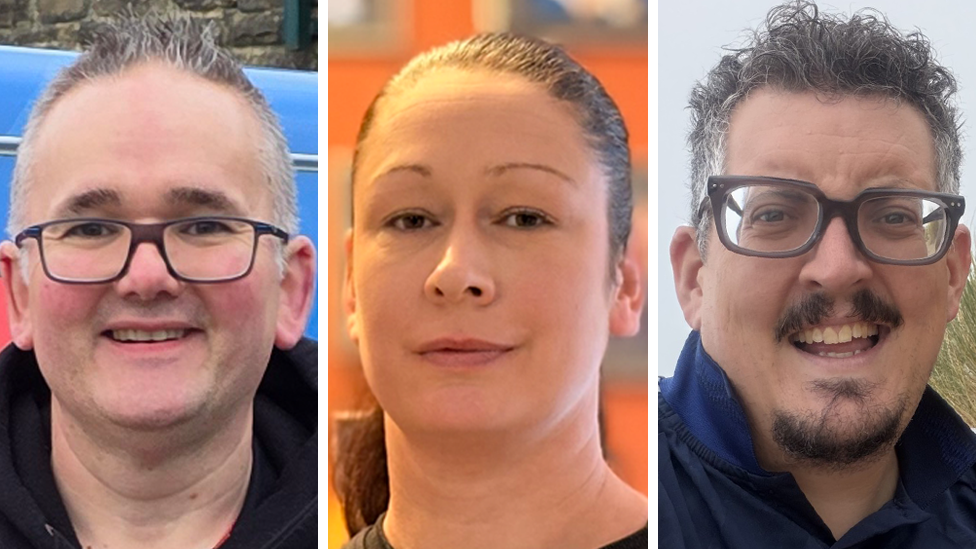
For some, it could mean extra financial pressure at a time when they are already struggling with the cost of living. The BBC spoke to three people about how they could be affected.
‘Our tracker mortgage will go up’
 Image source, Peter Gill
Peter Gill, 48, is one of the around 1.3 million Britons on a variable rate mortgage.
These loans track the Bank of England base rate, with a margin on top determined by the lender, so any rise in interest rates can push up repayments.
Peter, who runs a small tiling business in Halifax, says his monthly repayments will go up by roughly £45 following Thursday’s quarter-percentage point increase and he’s worried they could climb higher.
But he still thinks it’d be more expensive to move onto a fixed-rate deal – which is when you pay a set amount of monthly interest for a period – and is prepared to stay put for now.
To play this video you need to enable JavaScript in your browser.
This video can not be played
His higher mortgage costs come as the “cost of everything is going up”, he says.
The father of two, who has a combined household income of £45,000 with his wife Faye, is having to pay his staff more because of increases in the national minimum wage. Raw material costs have also risen due to the war in Iran.
At home, the family’s food, gas and electricity bills have gone up and he says he’s working “about six and a half days a week” to shield them from the worst of it.
“From my point of view, inflation goes up which costs you, then interest rates go up and you have even less money.”
‘My mortgage is going up by £200 a month’
 Image source, Ben Schofield/BBC
Most UK mortgage holders are on fixed-rate deals, but that doesn’t necessarily protect them when the Bank of England puts up rates.
David Hollingworth, from brokers L&C Mortgages, says many people will be shocked at how much higher fixed-rate deals are than they were five years ago following recent increases.
“Fixed rates have already risen due to market anticipation that interest rates would need to rise to combat higher inflation,” he says.
Dawn Fazackerley-King is a Pilates instructor who lives near Ipswich and has previously spoken to the BBC about her struggles with the cost of living.
She was on a five-year fixed deal at 1.4%, which she took out in January 2022. But the mother of two is about to refix for two years and the best deal she can find is a 5.69% loan. That will push her costs up by about £200 a month.
“I don’t know where that money is going to come from, it’s something we are going to have to figure out as a family. It’s stressful.”
She and her husband, who have a joint income of about £70,000, have already gone through their direct debits and there’s “no more obvious fat to trim”.
There is also no scope for them to take on additional work, as they both work full time.
“We’re still living in the same property, our household costs are remaining the same,” Dawn says. “It’s an additional cost of several hundred pounds but we’re not getting anything extra for that.”
‘My credit card repayments could rise’
 Image source, Ben Thomas
When the Bank of England increases its base rate, credit card borrowing costs also tend to increase, although the impact is not always immediate.
It may affect people with outstanding debts, as providers can increase the interest rates they charge with 30 days’ notice.
Ben Thomas, 41, from Shropshire, ditched his career as a chartered accountant during the Covid pandemic after a mental health crisis and retrained as a paramedic.
But the drop in income left him reliant on credit cards and personal loans for everyday living expenses and he is now £52,000 in debt.
-
Faisal Islam: How high will interest rates go?
-
Published1 day ago
-
-
Three ways the interest rate rise could affect you
-
Published1 day ago
-
Ben says he’s reached an agreement to pause the interest on most of it, but he is still incurring charges on around £2,000 of credit card debt and is worried about his repayments going up.
“With all that’s going on, rising interest rates is another cost to deal with,” he tells the BBC.
As well as overall debt repayments of around £300 a month, he and his wife pay £760 on their mortgage. They have also struggled with higher food and energy bills.
Simon Trevethick is head of communications at StepChange, which has been helping Ben manage his debt. He says the debt charity has seen a 20% increase in people asking for support this year and warned of tougher times ahead.
“If higher borrowing costs feed through into household budgets over the coming months, we could see further pressure on people seeking support.”
Disclaimer : This story is auto aggregated by a computer programme and has not been created or edited by DOWNTHENEWS. Publisher: BBC