With less than three weeks to go before the US midterm elections, the latest inflation data shows that the US inflation rate is not just accelerating, but that the impact on prices is broadening.
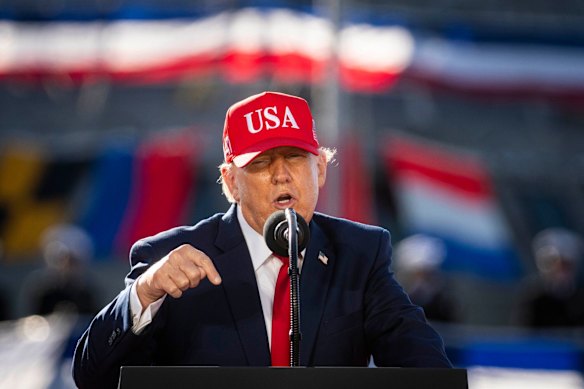
Given that the core issue in the election is affordability, the headline rise in the rate in September of 0.6 per cent – a material increase on the 0.4 per cent rise in August – and the year-on-year increase in prices of 3.7 per cent (3.4 per cent previously) couldn’t have come at a worse time for Donald Trump and the Republicans.
Economists had expected the rate to nudge up, not generate the biggest rise since April.
While the biggest contributor to the swelling inflation rate was energy prices, which accounted for more than half the overall rise, even on a “core” basis, which excludes energy and food costs, there was a 0.3 per cent increase in September and a 2.6 per cent increase from September last year.
The disparity between the headline and core rates suggests something quite unsettling for Trump; the Republicans facing election and Americans more generally: it’s not just the war in Iran and higher oil prices driving higher consumer prices.
Trump’s war in the Middle East has driven the oil price up from around $US70 a barrel to more than $US106 a barrel, with flow-on effects to the prices of gasoline and diesel, which have soared by 45 per cent and 70 per cent respectively from the levels before the February 28 attacks on Iran.
It appears that those increases in energy costs are now feeding into the wider economy as transport, travel, heating costs are rising.
They have yet to hit groceries, where prices rose only 1.8 per cent last month, but US food companies are saying increasing costs in the agricultural sector and the impact on their transport costs of the huge price spike for diesel is inevitably going to result in higher prices.
Even if the war Iran were to end soon, the shortages of diesel caused by the damage has done to Middle Eastern refinery infrastructure and the success Ukraine has had in targeting Russian refineries mean, the International Energy Agency said on Wednesday, that prices could start rising again. The world will remain short of diesel until the middle of next year, it said.
The IEA also said that the controversial deal Trump announced this week to ease sanctions on Russia and allow it to export diesel was “unlikely to materially affect” the amount of the fuel in the market – because of Russia’s dearth of operational refineries.
In any event, the volumes involved in that deal are too small to make much of a difference to prices. Trump has, unsurprisingly, overstated its potential.
While energy might be the biggest contributor to the lift in the inflation rate, it’s not, as indicated, the only one.
Prices for computers and related equipment are up almost 10 per cent over the past 12 months and software prices more than 28 per cent. That’s attributable to the boom in the artificial intelligence sector.
More disconcerting are rises in the cost of basic consumer goods like appliances, toys and apparel. Toys, for instance, were up 4.2 per cent in September. (Either consumers have ignored Trump’s advice to buy one doll rather than 30, or that one doll and other playthings have become a lot more expensive).
The spread of inflationary pressures into a broader range of goods and services may be partly a function of increased transport costs, but it may also be an indication that the delayed effects of Trump’s tariffs on the rest of the word are increasingly showing through.
The New York Federal Reserve Bank last week produced research that concluded that it could take up to 12 months for the full impact of increases in tariffs – including cost increases for us companies reliant on imported raw materials or components – to flow through to end prices.
The erratic way in which Trump’s raft of tariffs have been introduced, delayed, withdrawn (after being deemed illegal by the Supreme Court) and then replaced in July by yet another global suite, made it likely that their full impact would take time to emerge. That now seems to be happening.
The electoral damage of surging inflation is compounded by another data set released this week, which showed real hourly wages declining, relative to the same months last year, for the sixth successive month.
In September, they were down 0.7 per cent from September last year, adding to the sense of a “K-shaped” economy, where the wealthy have benefited from Trump’s big tax cuts and a buoyant stockmarket while average Americans are doing it increasingly hard.
The inflation data comes at an awkward time for the Federal Reserve Board, whose Open Market Committee – the body that sets the Fed’s policy rate – meets on the 27th and 28th of this month.
The Fed raised the federal funds rate 25 basis points last month, the first increase in more than three years.
Before the release of the inflation numbers, Fed officials had been talking down the prospect of an October rate rise, arguing that the impact of the war in the Middle East and Trump’s tariffs would fade and the rate would approach the Fed’s 2 per cent target some time next year.
Financial markets, which had factored in the near certainty of another rate hike in the immediate response to last month’s decision and the “hawkish” language from the Fed’s chair, Kevin Warsh, that accompanied it, had been progressively lowering the probability of an increase this month to negligible levels as it became clear from the minutes of the September meeting that the officials were less hawkish than Warsh’s commentary might have suggested.
After Wednesday’s data release, the odds on a rate rise priced into bond futures shot back up above 50 per cent, before subsiding to around 40 per cent.
The proximity to the elections probably argues against another rise, with the December meeting now looking far more likely.
The Fed has had enough run-ins with Trump, who wants it to force rates down to one per cent or below and has launched unprecedented legal attacks on board members in an attempt to wrest control of its decision-making, without provoking another.
Warsh, appointed by Trump with an expectation (or at least Trump’s expectation) that he would lower rates, could find himself, like his predecessor, Jerome Powell, targeted by Trump if the president thinks he has harmed Republicans’ electoral prospects and put him in personal jeopardy from a Democrat-controlled Congress.
The erratic way in which Trump’s raft of tariffs have been introduced, delayed, withdrawn and then replaced in July by yet another global suite, made it likely that their full impact would take time to emerge. That now seems to be happening.
While an October rate rise might be unlikely, barring something out of left field it makes a near-certainty of one before the end of the year. The US sharemarket fell and yields at the shorter end of the bond market rose in response to the inflation data.
The PHLX Semiconductor Sector Index, which reflects the performance of the big chip designers and manufacturers that are central to the AI boom, fell 4.3 per cent on the news, taking its decline over the past 10 days to more than 11 per cent. The Nasdaq index was down almost 2 per cent.
Tech stocks, particularly those directly engaged in the AI frenzy, are very sensitive to movements in interest rates because an increase in rates shrinks the current value of their future revenues and profits, if any.
A rising rate environment – which is near-certain unless the inflation rate reverses its trajectory – is a significant threat to the AI boom, as it is to the Republicans’ Congressional majorities and Trump’s ability to do as he likes in a second half of his term that would likely be studded with impeachment threats to him and the family his first two years in the White House have enriched.
The Business Briefing newsletter delivers major stories, exclusive coverage and expert opinion. Sign up to get it every weekday morning.
From our partners
Disclaimer : This story is auto aggregated by a computer programme and has not been created or edited by DOWNTHENEWS. Publisher: www.smh.com.au