There’s a certain tone, and maybe head tilt, friends give me when they want to talk about money. It’s usually accompanied by a: “Hey, Nicole”.
It often happens at trigger points in their lives – the points where most of us suddenly get serious, or at least curious, about savvy financial strategy. Graduating and starting work, getting married, definitely, having a baby, are some. Divorce, turning 50, the scary realisation you’re not far from drawing down your super and it’s looking sad, are others.
No matter what the trigger, there’s a simple piece of advice I give first, before going into detail. It’s this: You control your money, it doesn’t control you!
Here are my three oft-repeated, all-important follow-up points.
Recognise your in-built financial biases
A sense of empowerment versus impotence is vital, and that is especially so in a cost-of-living crisis where interest rates are going up and property prices falling.
Your economic comfort is to some extent determined by your money coming in and going out, although you have more influence over that than you may think. In fact, it’s possible you can make positive changes today.
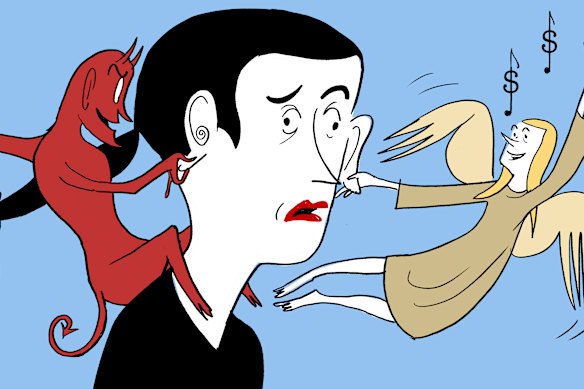
Forget the Reserve Bank rates or shock taxes in the budget – the real financial obstacles to overcome may be inbuilt psychological saboteurs. Here (as almost everywhere), your childhood plays a big part.
Think about your attitude to money. Is it an absorption or a reaction to your experiences and observations about money growing up: anxiety over bills, fights perhaps? What about holidays or nice things? Maybe you had insufficient money to do fun stuff. Or our parents uttered possibly even more destructive words:“But we’ll do it anyway”.
These formative experiences are subsumed into your own financial fabric, and you need to recognise that to overcome them.
Effective thinking for good wealth is the same as for good health. Start thinking of it like this and your finances may get more focused.
Figure out what you really want
You shouldn’t seek money for money’s sake, but for the options and opportunities it can bring you to create the life you want to lead.
All of us need strong motivation to resist instant gratification – that’s a human condition. The reality, though, is that some of us are better at a long-term focus than others. Successfully managing money is easier if you can project forward to the gain, not the pain.
Effective thinking for good wealth is the same as for good health. Start thinking of it like this and your finances may get more focused. Which brings me to the crux of the matter: How are you ever going to arrive financially if you don’t know where you’re going?
Only the most disciplined person can stash cash purely for stashing’s sake. The rest of us mere money mortals need a reason, and that reason needs to be so sweet you can almost taste it. That might be saving to take a year off to travel through Europe, buying a new car loan-free, or doing whatever floats your boat enough to mobilise and prioritise your money.
But it’s not enough to set these delicious goals. You should also cost and then calendar them. Here’s how:
- Figure out how much they are going to cost
- Determine when you want to enjoy them, and then
- Divide the cost by the number of pays in the interim period, to see if it’s feasible to hit your target date.
If your saving schedule isn’t feasible, you may have to delay a little. There may also be concurrent, competing goals requiring decisions about what to prioritise. And only at this point when chatting to friends about finances do I give specific money intel.
Know how to get what you want
That pep talk is followed by me introducing some easy but highly effective ideas into the conversation. They are:
- Salary sacrifice into super. Super’s tax treatment means more money goes in than you would receive in the hand.
- Start micro-investing outside of super. Fractional investment apps like Raiz and Sharesies let you regularly invest small amounts that you will barely miss. Left alone, returns quickly grow by harnessing the power of compounding.
- Pay down debt fast. It will stop the power of compounding working against you.
- And finally: automate your affluence. You can do this with all of the above points, by salary sacrificing to super through your employer or scheduling direct debits to micro-invest or pay down debt.
Try to remove the possibility of life’s busyness getting in the way of your long-term goals. If you understand how to direct and determine your financial future, everything can be a bunch easier.
Nicole Pedersen-McKinnon is author of How to Get Mortgage-Free Like Me, available at nicolessmartmoney.com. Follow her on Facebook, X and Instagram.
- Advice given in this article is general in nature and is not intended to influence readers’ decisions about investing or financial products. They should always seek their own professional advice that takes into account their own personal circumstances before making any financial decisions.
Expert tips on how to save, invest and make the most of your money delivered to your inbox every Sunday. Sign up for our Real Money newsletter.
From our partners
Disclaimer : This story is auto aggregated by a computer programme and has not been created or edited by DOWNTHENEWS. Publisher: www.smh.com.au