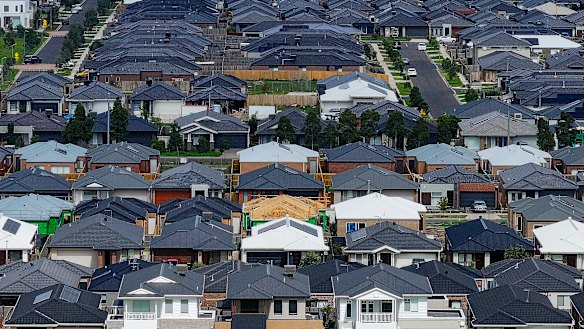

As interest rates hit 18-year highs, households stretched by their mortgages are naturally on the hunt for anything that will ease the pain.
Supermarkets see all sorts of examples of this, from strong sales of home brand products, to shoppers embracing cheaper food options such as mince, or a surge in customers chasing down specials at rivals (so-called “cross shopping”).
But how to ease the pain on many households’ biggest expense, their home loan?
The banking equivalent to scanning the Aldi catalogue for specials is refinancing: dumping your bank for a cheaper rival. However, recent figures suggest there’s a significant cohort of borrowers who may struggle to do this, even if it would make a lot of sense for them to do so.
That’s because of a problem dubbed “mortgage prison” – where customers effectively get stuck with their bank because they can’t meet the lending criteria needed to switch to a rival.
This year’s five interest rate hikes are bound to stoke more interest in switching banks, as that’s often how you get the most competitive interest rates.
The combination of rising interest rates and falling house prices is a grim double whammy for stretched first home buyers.
Yet recent figures from the credit bureau Equifax suggest there is a generational gap between those who can switch banks to get a better home-loan deal, and those who cannot.
Last week it said the overall amount of refinancing to a different lender had fallen 8.8 per cent in the year to September, and the trend was particularly stark for younger borrowers.
It said refinancing demand for people aged between 26 and 35 had fallen 14.2 per cent in the period, while for people aged between 56 and 60, or over 60-year-olds, refinancing demand had moved slightly higher.
“Older homeowners with higher equity and lower loan balances retain the flexibility to negotiate or refinance, mitigating some of the pressure from successive rate hikes,” said executive general manager at Equifax Australia, Moses Samaha. “Younger Australians, on the other hand, are facing a tougher proposition.”
As rates have risen, mortgage brokers have also been warning of the perils of mortgage prison. There are a couple of reasons why more people find themselves in this predicament.
One is that banks must test how prospective new borrowers would fare under higher interest rates – including people who are refinancing from a rival. This stress test involves adding 3 percentage points (known as a serviceability buffer) to the current home-loan rate, and estimating how a prospective customer would cope. Today, this may well mean testing if a borrower can afford a rate of about 9.5 per cent.
Recent first home buyers are particularly likely to be knocked back by this test because they’re often highly geared, after loading up on debt to scrape into the property market.
But higher interest rate stress tests are not the only challenge recent first home buyers face. Banks also look at the value of a prospective borrower’s house, which will have fallen lately thanks to the property market slump.
For people who’ve owned their property for a long time, recent falls are probably small when compared with the longer-term gains they’ve made. But recent buyers haven’t had the benefit of those price gains, and often they’ve also borrowed a large proportion of the property’s value to get a foot in the door.
That can cause a rise in their loan-to-valuation ratio – another metric looked at by banks – and in some cases it might mean people who want to switch banks must pay the added cost of mortgage insurance.
To be fair, some do manage to escape mortgage prison, as banks are allowed to provide an exemption to serviceability rules in some cases. Canstar reported in September that the share of new loans processed as “exemptions” hit a record high of 5.8 per cent of all new loans settled in the quarter.
Unfortunately, however, the combination of rising interest rates and falling house prices is a grim double whammy for stretched first home buyers who might want to switch to a better deal. And mortgage prison will remain a risk until the Reserve Bank decides it’s time for rates to start coming down.
All in all, it’s an example of how there’s nothing particularly fair about monetary policy – using interest rates to target inflation. No wonder it’s known as a “blunt instrument”.
The Business Briefing newsletter delivers major stories, exclusive coverage and expert opinion. Sign up to get it every weekday morning.
 Clancy Yeates is deputy business editor. He has covered banking and financial services, and was previously national business correspondent in the Canberra bureau.Connect via X or email.
From our partners
Disclaimer : This story is auto aggregated by a computer programme and has not been created or edited by DOWNTHENEWS. Publisher: www.smh.com.au