Melbourne is set to exit the $1 million club by the end of the year, after its median house price shed 3.3 per cent, or about $34,000, in the September quarter.
Melbourne’s median house price is now $1,014,335, the latest Domain House Price Report, released on Thursday, showed. If it falls another 1.5 per cent, it would be in the high $900,000s.
The last time Melbourne’s house prices were below $1 million was in the March quarter of 2021.
Domain’s chief residential economist Dr Nicola Powell predicted a fall below the million dollar mark by December, as the impact of the latest interest rate rise in September is yet to be felt, while buyers deal with a higher cost of living.
Banks including ANZ and Westpac are predicting another rate hike by the Reserve Bank in November. Morgan Stanley analysts on Wednesday forecast Australian housing prices to fall by 10 to 15 per cent by the end of next year.
For those already in the market, Melbourne’s supply of homes for sale was the highest since September 2014, giving buyers more choice and pushing prices down, Powell said.
“I think it’s all of the above factors that are influencing all of our markets at the moment,” she said. “It is quite confronting when you look at it, this is a market that has been undervalued for some time, and it is now at a more than five-year low.”
While house prices were down, Melbourne’s unit prices also fell -3.7 per cent over the three months to September to a $563,199 median.
House and unit prices fell in every region, pointing to a broad-based downturn, Powell said.
The most expensive areas fell most with house prices in the inner south plummeting -7.7 per cent over the September quarter to $1.43 million. Those in the inner east fell -3.6 per cent.
Prices also fell in more affordable areas over the quarter, albeit more modestly.
Ray White West’s Hammad Agog said the local market had been affected by rising interest rates, but it was also opening up opportunities.
“There’s definitely more bargain hunters out there now,” Agog said.
Buyers were moving from more expensive inner-city areas to suburbs like Sunshine, to get a bigger bang for their buck, he said, while local buyers were also in the market.
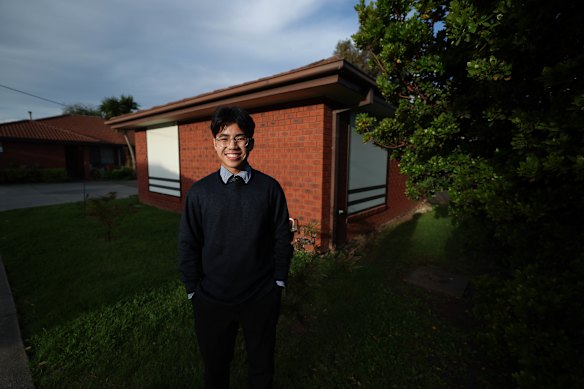
That included first home buyers like David Bouttaveth who recently bought a unit in Deer Park with Agog’s help.
The 23-year-old, who has been working full-time for around four years, saved a deposit while living at home. Though he contributed financially to the household, he did not pay rent.
The reality for many buyers is that being able to save for a deposit is still not easy, even in a falling market, and Bouttaveth said he would not have been able to without help.
“It definitely helped the savings living at home with the folks,” Bouttaveth said. “If I moved out and had to pay rent it would have been harder.”
Bouttaveth said he had always been “conservative” with his money, saving rather than spending on luxuries.
In Melbourne’s higher priced suburbs, home sellers are facing a down market, with those at the top end – including $5 million-plus properties – cutting their prices.
“We’ve seen vendors need to adjust their prices by $1 million to sell,” principal at Belle Property Brighton and St Kilda Sam Inan said.
He said the upcoming Victorian state election was also having an impact, as business people at the top end of the market decided to wait for the result before transacting.
The state government introduced higher land taxes for second-home owners or investors from 2024, to recoup COVID debt.
The government and opposition have both vowed to roll back the taxes as part of their election promises.
Meanwhile, interstate investors have snapped up properties for their lower prices and higher yields.
“Rents look great compared to what investors are paying for a property,” Inan said.
While Melbourne’s property market weathers the downturn, there is some hope on the horizon, AMP’s deputy chief economist Diana Mousina said.
“If you’re looking for a silver lining, the pace of the falls is slowing a bit,” Mousina said.
Melbourne’s house prices should bottom out before the other capitals, given prices are lower, meaning a faster recovery.
AMP predicts a total dwelling price fall (both houses and units) of 11 per cent in Melbourne, with both already down 7 per cent.
“There could be a little bit more to go on that front … by the middle of next year prices will bottom out,” she said.
Property alerts are now available in The Age app. Turn them on to receive the latest market news and trends.
Property listings
From our partners
Disclaimer : This story is auto aggregated by a computer programme and has not been created or edited by DOWNTHENEWS. Publisher: www.smh.com.au