As a credit card writer, one of the most common questions I get is, “How many credit cards should I have?”
While I personally see the value in having multiple cards to maximize rewards, I also know that not everyone wants to juggle annual fees, statement credits and bonus categories. And the good news is, you don’t need a wallet full of cards to earn rewards.
Whether you’re looking for flexible travel rewards, valuable perks or simple cash back, there are plenty of cards that can stand on their own.
Here are some of the best credit cards if you want only one in your wallet.
Overview of the best stand-alone cards
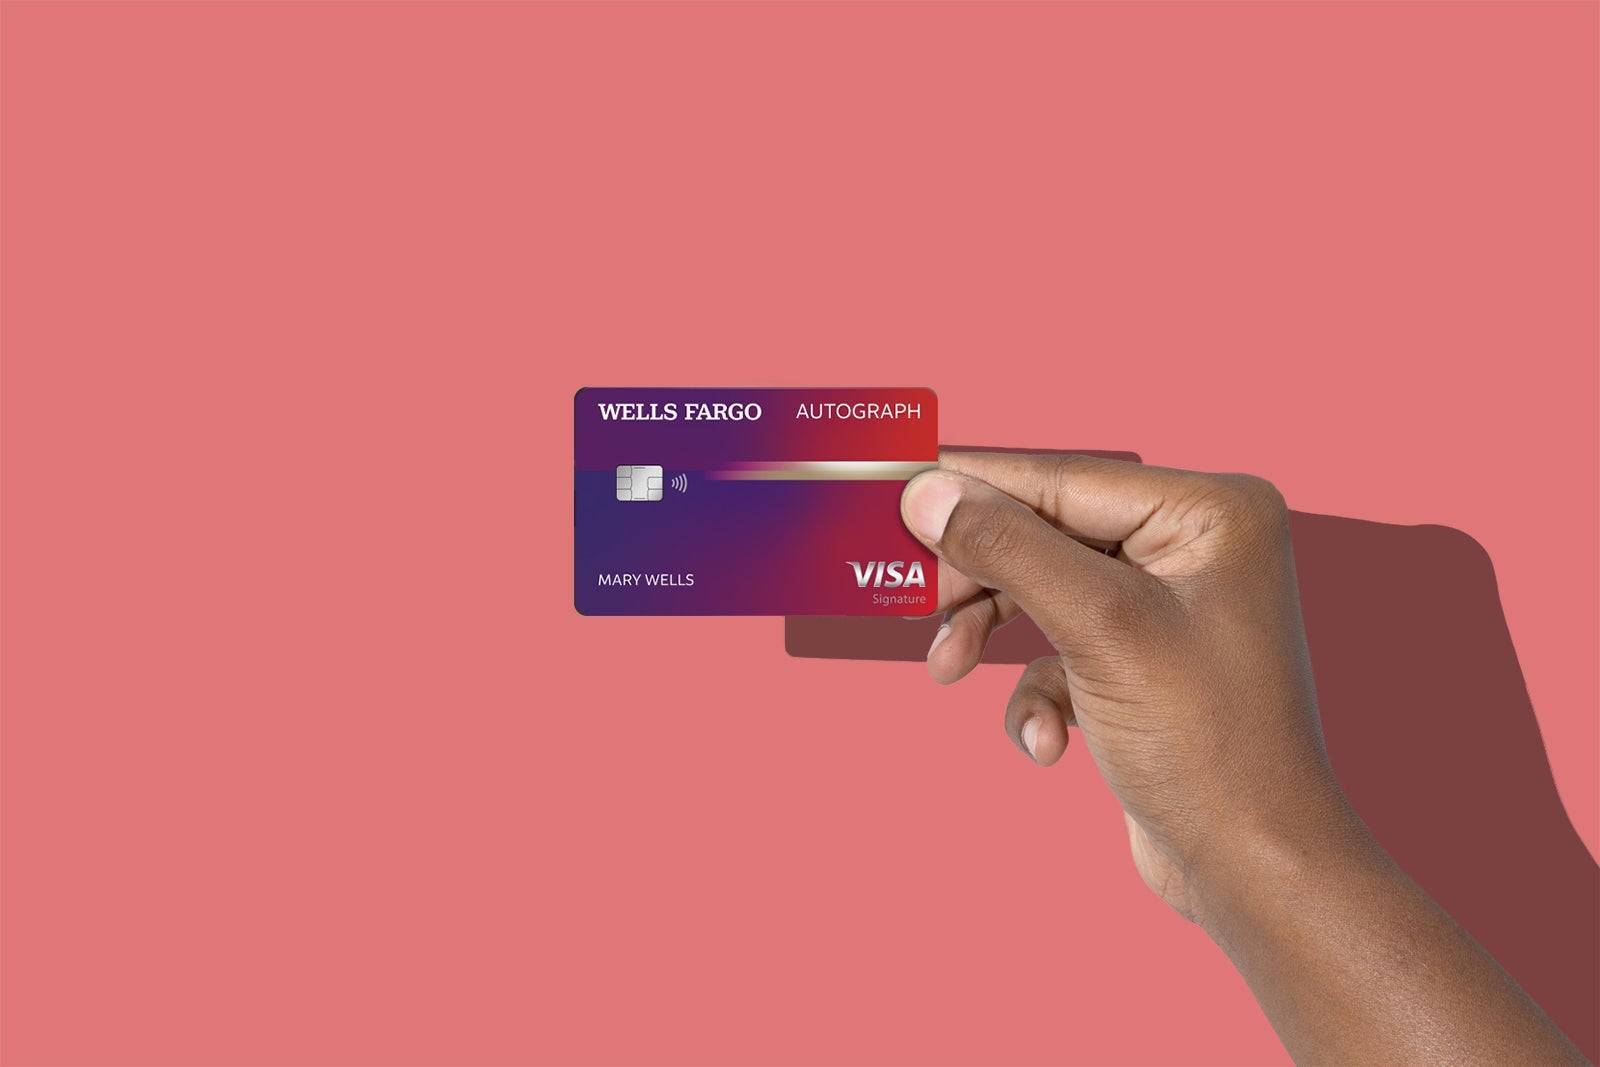
Wells Fargo Autograph
For someone who wants travel rewards without paying an annual fee, the Wells Fargo Autograph is one of the best options for a one-card wallet.
Welcome bonus: Earn 20,000 bonus points when you spend $1,000 on purchases in the first three months from account opening.
Welcome offer value: $350 (per TPG’s October 2026 valuations)
Annual fee: $0
Why we chose it: The Autograph is designed for everyday spending, with bonus categories covering purchases that many people make regularly.

Daily Newsletter
Reward your inbox with the TPG Daily newsletter
Join over 700,000 readers for breaking news, in-depth guides and exclusive deals from TPG’s experts
By signing up, you will receive newsletters and promotional content and agree to our Terms of Use and acknowledge the data practices in our Privacy Policy. You may unsubscribe at any time.
Cardholders can earn bonus points on categories such as restaurants, travel, gas stations, transit, streaming services and phone plans.
The card also earns transferable Wells Fargo Rewards, giving travelers more flexibility than they might expect from a no-annual-fee card.
In fact, the Autograph got top honors as the No-Annual-Fee Credit Card of the Year at the 2026 TPG Awards, thanks in part to its strong everyday earning rates and access to transfer partners.
To learn more, check out our full review of the Wells Fargo Autograph.
Apply here: Wells Fargo Autograph
Wells Fargo Active Cash
If you want to keep your wallet as simple as possible and would rather earn cash rewards than points and miles, the Wells Fargo Active Cash is worth a closer look.
Welcome bonus: Earn $100 cash rewards after spending $500 on purchases in the first three months from account opening.
Welcome offer value: $100
Annual fee: $0

Why we chose it: The Active Cash is one of the simplest cards on this list, earning 2% cash rewards on all purchases without any bonus categories to track.
That means you can use the same card for groceries, dining, travel and other everyday expenses without worrying about whether you’re maximizing your rewards.
The card also offers a handful of useful benefits, including cellphone protection when you pay your monthly phone bill with the card (subject to a $25 deductible and other limitations).
The biggest drawback is that the Active Cash charges foreign transaction fees and doesn’t offer the same travel perks or redemption flexibility as some of the other cards on this list. Still, if your priority is earning cash rewards without paying an annual fee, it’s an excellent one-card option.
To learn more, check out our full review of the Wells Fargo Active Cash.
Apply here: Wells Fargo Active Cash
Capital One Venture Rewards
If you want to earn travel rewards without keeping track of a long list of bonus categories, the Capital One Venture Rewards is a strong option for your sole card.
Welcome bonus: Earn 75,000 bonus miles after spending $4,000 on purchases within the first three months from account opening. Plus, receive a $300 credit to use on hotels and vacation rentals booked through Capital One Travel in the first cardholder year upon account opening.
Welcome offer value: $1,688, including the credit (per TPG’s valuations)
Annual fee: $95
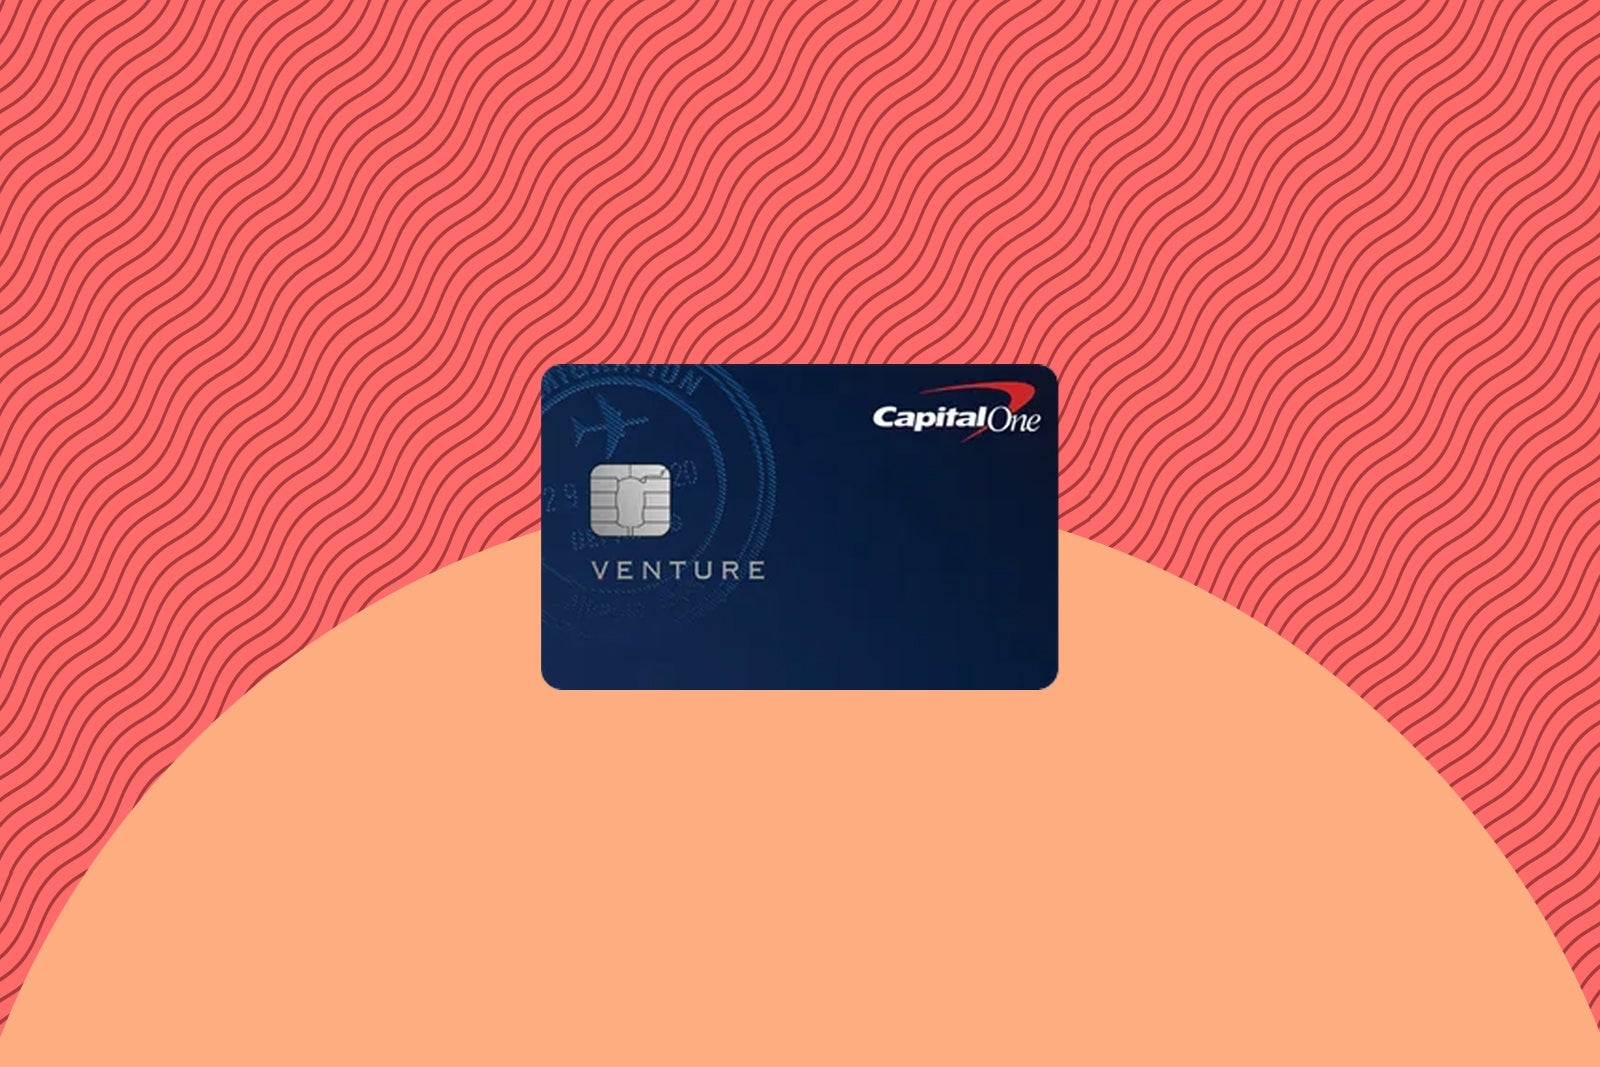
Why we chose it: The Venture Rewards keeps things simple. You’ll earn at least 2 miles per dollar on every purchase, so you don’t have to remember which card to use for groceries, dining, gas or other everyday expenses. You’ll also earn 5 miles per dollar on hotels, vacation rentals and rental cars booked through Capital One Travel.
Rather than trying to build a strategy around several cards and their individual bonus categories, you can put virtually all of your spending on the Venture Rewards and earn a consistent return.
Capital One miles can also be transferred to over 15 airline and hotel loyalty programs, giving you the option to get more value from your rewards when you’re willing to put in a little more effort. Or, you can use your miles to offset eligible travel purchases at a fixed value if you prefer a simpler approach.
Learn more: Capital One Venture Rewards Credit Card
Chase Sapphire Preferred
For someone who wants a single card that earns transferable points and offers a broad range of travel benefits without a premium annual fee, the Chase Sapphire Preferred is one of my top recommendations.
Welcome bonus: Earn 75,000 bonus points after spending $5,000 on purchases in the first three months from account opening.
Welcome offer value: $1,538 (per TPG’s valuations)
Annual fee: $95
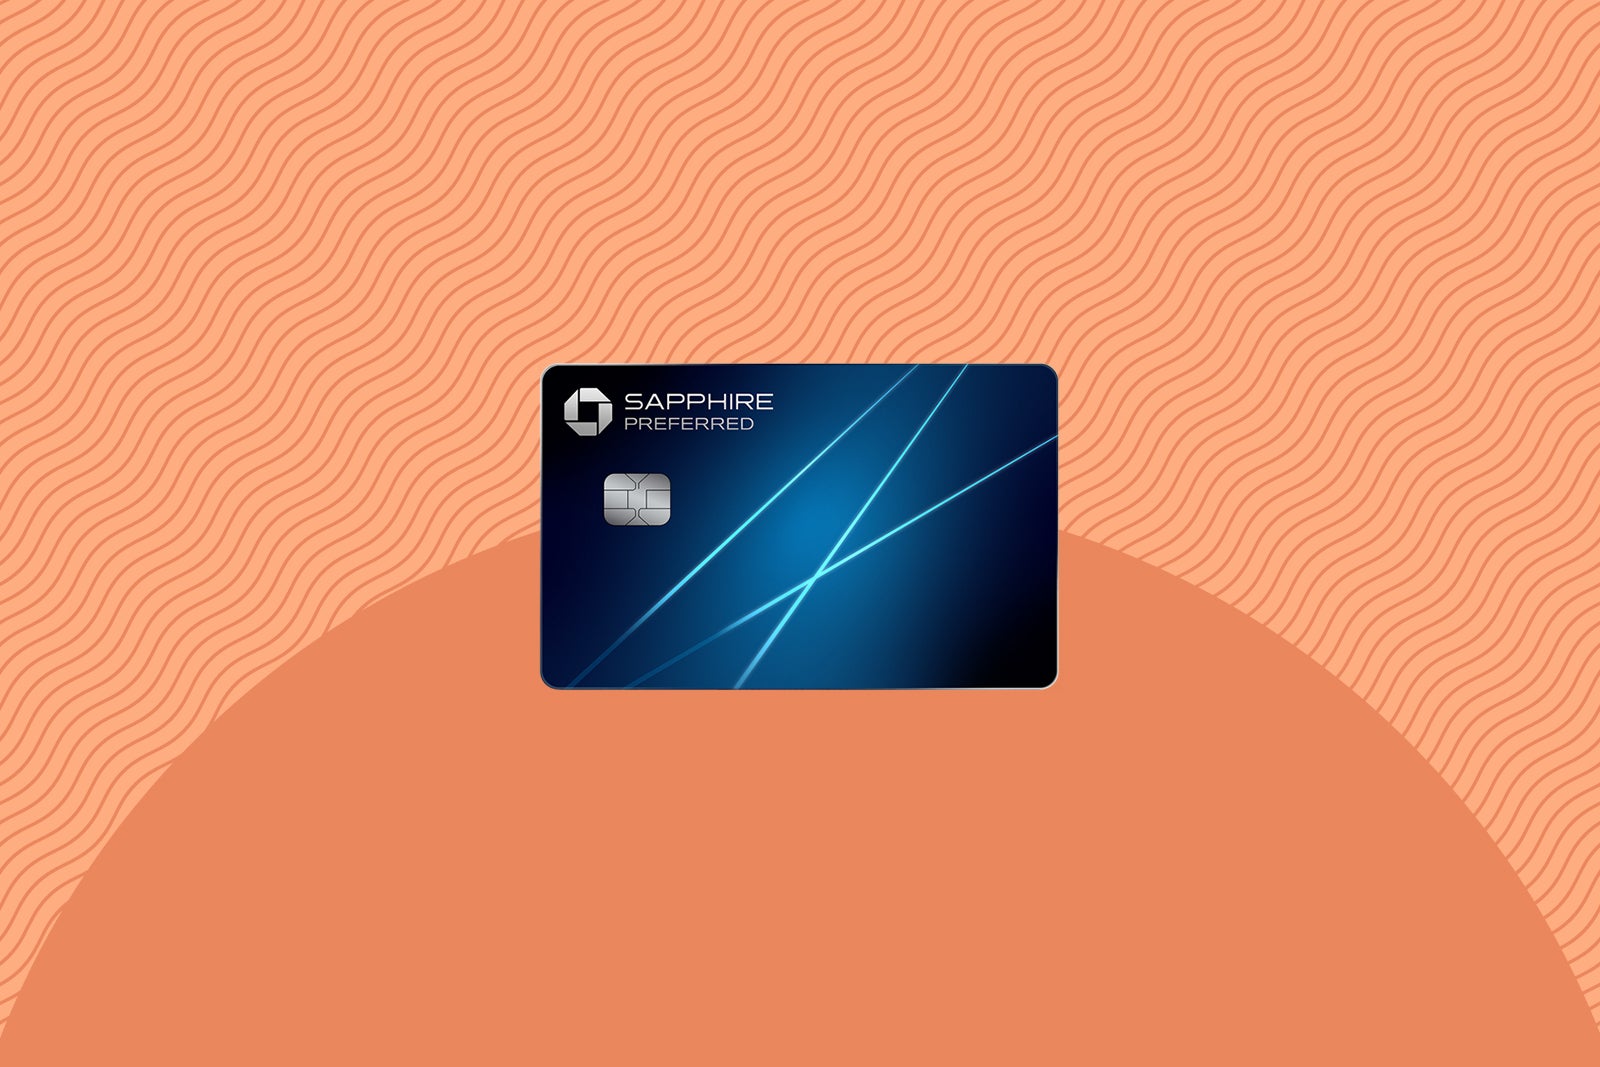
Why we chose it: The Sapphire Preferred has long been one of TPG’s favorite travel cards, and I think it’s a great fit for someone who wants one card rather than an entire points and miles strategy.
You’ll earn 5 points per dollar spent on travel purchased through Chase Travel℠, 3 points per dollar spent on gas and electric vehicle charging, 3 points per dollar spent on vacation rentals at top brands (including Airbnb and Vrbo), 3 points per dollar spent on dining, select streaming services and online grocery (excluding Walmart, Target, and wholesale clubs) purchases and 2 points per dollar on other travel purchases.
The card also comes with a $100 annual hotel credit for bookings through Chase Travel.
But perhaps the biggest reason I’d consider the Sapphire Preferred as a one-card setup is the flexibility of Chase Ultimate Rewards. You can redeem your points through Chase Travel or transfer them to Chase’s airline and hotel partners, giving you plenty of options as your travel habits evolve.
To learn more, check out our full review of the Chase Sapphire Preferred.
Apply here: Chase Sapphire Preferred
Citi Strata Premier
The Citi Strata Premier is a strong choice if you want one card that rewards a broad mix of everyday purchases while giving you access to a transferable points program.
Welcome bonus: Earn 60,000 bonus points after spending $4,000 on purchases in the first three months of account opening.
Welcome offer value: $1,140 (per TPG’s valuations)
Annual fee: $95 (see rates and fees)
Why we chose it: The Strata Premier has a useful combination of bonus categories, making it easier to earn more rewards without juggling multiple cards.
The card earns bonus points across several categories, including air travel, restaurants, supermarkets and gas stations, making it a good fit for someone whose spending is spread across several areas.
Citi ThankYou Rewards also lets you transfer your points to Citi’s airline and hotel partners, which can make the rewards considerably more valuable than a simple cash-back setup for travelers willing to learn the ropes.
If you want a balance of everyday earning potential and flexible travel rewards, this card is worth considering.
To learn more, check out our full review of the Citi Strata Premier.
Apply here: Citi Strata Premier
American Express Gold
If most of your spending goes toward restaurants and groceries, the Amex Gold can be a rewarding choice for a one-card wallet.
Welcome bonus: Find out your offer and see if you are eligible for as high as 100,000 Membership Rewards points after spending $8,000 on eligible purchases in your first six months of card membership. (Welcome offers vary, and you may not be eligible for an offer.)
Welcome offer value: Up to $2,000 (per TPG’s valuations)
Annual fee: $325
Why we chose it: The Amex Gold stands out for its earning rates on two of the biggest everyday spending categories: dining and U.S. supermarkets.
You’ll earn 4 points per dollar spent on up to $25,000 in purchases at U.S. supermarkets per calendar year (then 1 point per dollar) and 4 points per dollar spent on dining at restaurants worldwide (on up to $50,000 per calendar year, then 1 point per dollar). You’ll also earn 3 points per dollar spent on flights booked directly with airlines or through amextravel.com or the Amex Travel App™.
The card also comes with a collection of statement credits that can help offset its annual fee, though you’ll need to use them to get their full value (enrollment required for select benefits).
The biggest downside to using the Amex Gold as your only card is its relatively low 1-point-per-dollar earning rate on purchases outside its bonus categories. Still, if dining and groceries make up a large portion of your spending, the higher earning rates can make up for that.
Note that American Express isn’t as widely accepted as Visa or Mastercard in some international destinations, so you may need a backup card when traveling abroad.
To learn more, check out our full review of the Amex Gold.
Apply here: American Express Gold
Capital One Venture X
If you want one credit card to provide premium travel perks without a high annual fee, the Venture X is tough to beat.
Welcome bonus: Earn 75,000 bonus miles after spending $4,000 on purchases in the first three months from account opening.
Welcome offer value: $1,388 (per TPG’s valuations)
Annual fee: $395
Why we chose it: The Venture X is one of the few premium cards that can make sense as a one-card wallet because its benefits extend well beyond its earning rates.
Cardholders earn 2 miles per dollar on everyday purchases, 5 miles per dollar on flights and vacation rentals booked through Capital One Travel and 10 miles per dollar on hotels and rental cars booked through the portal.
The Venture X is consistently one of my most-used cards, largely because I know I’ll earn at least 2 miles per dollar on every purchase, regardless of the spending category.
The card also comes with a $300 annual credit for bookings made through Capital One Travel and 10,000 miles on your account anniversary each year, which, if fully utilized, can completely offset the card’s annual fee.
Beyond that, the Venture X provides lounge access, travel protections and other premium benefits that would otherwise require a separate travel card.
Learn more: Capital One Venture X
American Express Platinum
If you want your one card to focus heavily on luxury travel benefits and you don’t mind paying a premium annual fee, the Amex Platinum is a top option.
Welcome bonus: New cardmembers can find out their offer and may be eligible for as high as 175,000 bonus points after spending $12,000 on purchases in the first six months of card membership. (Welcome offers vary, and you may not be eligible for an offer.)
Welcome offer value: Up to $3,500 (per TPG’s valuations)
Annual fee: $895
Why we chose it: The Amex Platinum is less about putting every purchase on one card and more about maximizing value from a single premium travel card.
It offers an extensive collection of travel and lifestyle benefits, including access to a wide range of airport lounges, statement credits and other premium perks. For frequent travelers who can naturally use many of those benefits, it can effectively replace several other cards in a wallet.
The trade-off is that the Platinum isn’t particularly strong for everyday spending. If you’re using only one card, you’ll want to make sure you’re comfortable sacrificing some earning potential in exchange for the card’s benefits. And like the Amex Gold, note that American Express acceptance can be more limited abroad.
I’d recommend it as a one-card option primarily for frequent travelers who value premium perks and can make good use of its credits.
To learn more, check out our full review of the Amex Platinum.
Apply here: American Express Platinum
How we picked the best stand-alone cards
Choosing a single credit card is different from choosing cards to fill specific roles in a larger wallet. If you’re only going to have one card, it needs to be versatile enough to earn rewards across a variety of purchases and valuable enough to justify keeping long-term.
For this list, we considered several factors:
- Earning potential: How well each card rewards common everyday purchases, as well as whether it offers a strong baseline earning rate on spending that doesn’t qualify for a bonus category.
- Reward flexibility: Transferable points and miles can give you more options than a single-purpose rewards currency.
- Travel benefits: For travel cards, we considered perks such as travel credits, lounge access, travel protections and other benefits that can make a single card more useful.
- Annual fee and benefits: A card with a high annual fee must provide sufficient ongoing value to justify the cost.
We also considered the flexibility each card offers for different types of consumers. There’s no single card that is best for everyone, which is why this list includes options for frequent travelers, foodies, cash-back enthusiasts and people who simply want to keep things as easy as possible.
Bottom line
You don’t need five, 10 or 20 credit cards to get plenty of value from your spending. If managing multiple cards sounds like too much work, a well-chosen single card can still help you earn points, miles or cash back on everyday purchases.
As someone who spends a lot of time thinking about how to maximize credit card rewards, I’d still generally recommend a multi-card strategy for those willing to put in the effort.
But if simplicity is your priority, there’s nothing wrong with sticking to one card. The right card can deliver plenty of value without turning your wallet into a full-time job.
Related: How to choose the best credit card for you
For rates and fees of the Amex Gold, please click here.
For rates and fees of the Amex Platinum, please click here.
Disclaimer : This story is auto aggregated by a computer programme and has not been created or edited by DOWNTHENEWS. Publisher: thepointsguy.com