If you’re looking for a business credit card that’s easy to use and doesn’t require you to memorize bonus categories, the is worth a look. The no-annual-fee card earns at least 2% cash back on purchases, making it a straightforward option for everyday business expenses.
The card gets more interesting if you already bank with U.S. Bank, since qualifying customers can earn up to 2.5% cash back on eligible purchases.
That said, I wouldn’t recommend opening a U.S. Bank business checking account just to get the higher earning rate. If you don’t already have a banking relationship with U.S. Bank, there are other business cards that may be a better fit. Card rating*: ⭐⭐⭐
*Card rating is based on the opinion of TPG’s editors and is not influenced by the card issuer.
U.S. Bank Business Essentials: The basics
The is a business cash-back card with a simple rewards structure and an industry-leading 2% base cash-back rate.
Here’s an overview:
- Annual fee: $0
- Welcome offer: Earn $500 cash back after spending $5,000 on purchases in the first 150 days from account opening.
- Earning rates: Earn unlimited 2% cash back on eligible purchases, up to 2.5% cash back on the first $10,000 in eligible purchases each billing cycle with qualifying U.S. Bank business checking balances, and 6% cash back on prepaid hotels and car rentals booked through the U.S. Bank Travel Center.
- Rewards: Cash back is earned as U.S. Bank points and can be redeemed for a statement credit or a deposit into an eligible U.S. Bank account, among other options.
The card’s biggest drawback is that unlocking its highest everyday earning rate requires maintaining a qualifying U.S. Bank business checking balance. Also, its elevated travel earning rate is limited to prepaid hotel and car rental bookings through the bank’s travel portal.
U.S. Bank Business Essentials pros and cons
| Pros | Cons |
|---|---|
|
|
U.S. Bank Business Essentials benefits
As a no-annual-fee business card, the offers relatively few additional benefits beyond its cash-back rewards.
Spending management tools
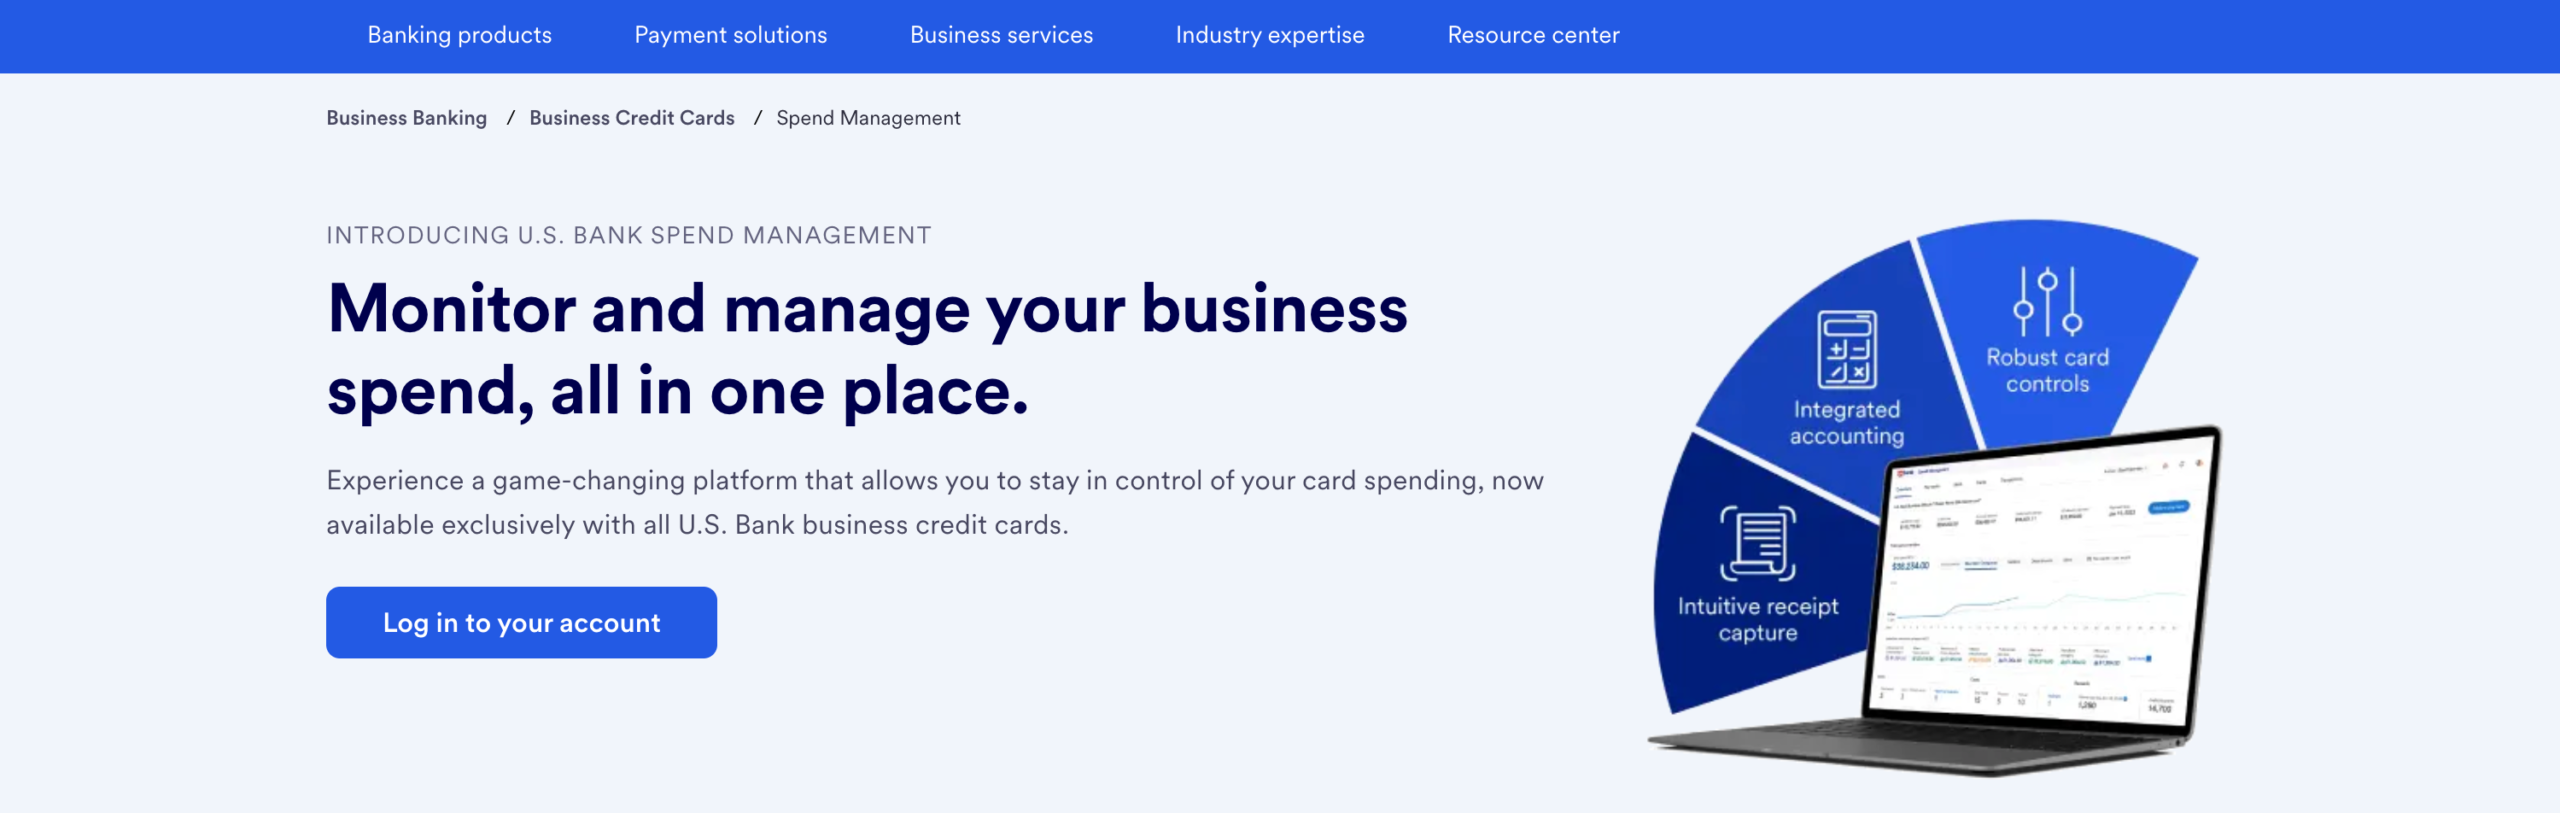
Cardholders get access to U.S. Bank’s free Spend Management Pro platform, which includes accounting integrations, employee card controls, receipt uploads and real-time expense tracking. (More advanced features require a paid subscription after a six-month trial.)
If you are a business owner and would use the platform, this is a nice perk, but I wouldn’t place much weight on this benefit.
How to earn and use rewards on the U.S. Bank Business Essentials
Earning rewards
The earns:
- A base 2% cash back on every eligible purchase
- 2.5% cash back on the first $10,000 in eligible purchases each billing cycle when paired with qualifying U.S. Bank business checking balances
- 6% cash back on prepaid hotels and car rentals booked through the U.S. Bank Travel Center
The card’s biggest selling point is its simplicity. The base 2% cash-back rate means you don’t have to remember bonus categories or change cards depending on what you’re buying, which could be compelling if you’re looking for a single card for everyday expenses.
Businesses that maintain a 30-day average balance of at least $10,000 across eligible U.S. Bank business checking accounts can earn an additional 0.5% cash back on the first $10,000 in eligible purchases each billing cycle.
That brings the total earning rate to 2.5% on those purchases, for up to $250 in cash back — $50 more than you’d earn at the card’s standard 2% rate.
If you already keep the required balance with U.S. Bank, I think this is a nice perk because there’s nothing else you need to do to change the way you earn rewards, and you’ll just get a little more cash back on spending you were already going to put on the card.
For everyone else, though, I’d consider whether the additional cash back is enough to justify moving your business banking relationship.
Finally, the 6% rate on prepaid hotels and car rentals is strong for a no-annual-fee card, but you’ll have to book through the U.S. Bank Travel Center to earn it.
Redeeming cash back
Although U.S. Bank markets the rewards as cash back, they’re technically earned as points. You can redeem your points as a deposit into an eligible U.S. Bank account or as a statement credit.
Other redemption options include travel, merchandise and gift cards, though the redemption value can vary depending on the option you choose.

For simplicity, I’d stick with a statement credit or an eligible U.S. Bank account deposit when redeeming these rewards.
Where the U.S. Bank Business Essentials falls short
The biggest drawback is that the ‘s best everyday earning rate comes with a fairly significant requirement. To earn 2.5% cash back, you’ll need to maintain a 30-day average balance of at least $10,000 in an eligible U.S. Bank business checking account.
Even then, the additional 0.5% applies to only the first $10,000 in eligible purchases each billing cycle. That means the banking relationship can generate at most $50 more in cash back per billing cycle than you’d earn with the card’s standard 2% rate.

That’s a solid bonus if you already bank with U.S. Bank and maintain the required balance, but I wouldn’t move $10,000 into a U.S. Bank business checking account solely to unlock the higher earning rate.
The card’s 6% cash-back category also requires you to book prepaid hotels and car rentals through the U.S. Bank Travel Center to earn that rate. If you’re already comfortable booking through a travel portal, it’s a nice way to boost your rewards. However, booking directly can make it easier to earn and use hotel elite status benefits and handle changes or cancellations, so I’d weigh those advantages against the additional cash back.
U.S. Bank Business Essentials vs. Business Essentials Plus
If you like the sound of the but have higher business expenses, its more premium sibling may offer better long-term value.
The U.S. Bank Business Essentials™ Plus Visa Signature® Card has a $295 annual fee but earns 5% cash back on your top eligible spending category each month (on up to $200,000 in annual purchases). That’s 3 percentage points more than the Business Essentials’ base 2% cash-back rate, meaning you’d need to spend $820 monthly in a qualifying category to offset the Plus’ annual fee.
The Plus also offers higher earning potential for businesses with qualifying U.S. Bank balances and earns 10% cash back on prepaid hotels and car rentals booked through the U.S. Bank Travel Center.
Unlike the Business Essentials, which charges a 3% foreign transaction fee, the Business Essentials Plus has no foreign transaction fee, making it a better option for purchases abroad.
If your spending isn’t high enough to offset the Plus’ annual fee, however, I’d stick with the no-annual-fee Business Essentials.
Related: How to redeem business card rewards for maximum value
The information for the U.S. Bank Business Essentials Plus card has been collected independently by The Points Guy. The card details on this page have not been reviewed or provided by the card issuer.
Is the U.S. Bank Business Essentials worth it?
The is worth considering if you want a no-annual-fee business card with a simple 2% cash-back rate, particularly if you already maintain qualifying balances with U.S. Bank.
If you’re not a U.S. Bank business banking customer, however, I’d compare it with other business cash-back cards before applying.
When to apply for the U.S. Bank Business Essentials
New cardholders can earn $500 cash back after spending $5,000 on purchases in the first 150 days from account opening.
While some business cards offer more valuable welcome bonuses, this one gives you five months to meet a relatively reasonable spending requirement.
I’d apply when you can comfortably meet the spending requirement through your normal business expenses.
Related: How to apply for a business card
Other cards to consider if you don’t want the U.S. Bank Business Essentials
If you like the idea of simple business cash back but don’t want to use U.S. Bank for your business banking, there are other alternatives worth considering.
For additional options, see our list of the best business credit cards.
The information for the U.S. Bank Triple Cash has been collected independently by The Points Guy. The card details on this page have not been reviewed or provided by the card issuer.
Bottom line
The is a solid no-annual-fee business cash-back card, but its strongest value proposition is aimed at U.S. Bank business banking customers.
I’d consider it if you already keep qualifying balances with U.S. Bank and want a simple way to earn up to 2.5% cash back on everyday business spending.
If you don’t have an existing U.S. Bank banking relationship, the standard 2% rate is still competitive, but you may find another business card offers a better fit for your spending habits.
For rates and fees of the Amex Blue Business Cash, click here.
Disclaimer : This story is auto aggregated by a computer programme and has not been created or edited by DOWNTHENEWS. Publisher: thepointsguy.com